12.4 business day average to clear to close

Forested cliffs over the water on the Acadia coast

Blog

Mortgage questions, answered plainly

Practical articles on Maine and Florida mortgages, relocation, and DSCR investor loans.

This is where I put mortgage questions into plain language. I am Travis Penny, a mortgage broker with Vision Mortgage. I work with buyers and homeowners in Maine and Florida, and I also arrange DSCR investor loans in the states listed on my Licensing page. An article may give you a useful starting point, but it cannot tell you whether a specific home, building, income file, or transaction will qualify. That takes a conversation about the actual details.

If you are buying in Maine, start with the Maine home loan guide or a town guide for the place you have in mind. If your plans lead south, the Florida home loan guide and Maine to Florida moving guide cover different parts of that decision. The details that matter can change from one property to another. A condo association, a proposed construction project, or an existing home that has not sold yet may call for a different path than an ordinary purchase.

For investors, the DSCR investor loan guide explains how rental income enters the review and why property documentation matters. For self employed buyers, bank statement loans and 1099 mortgages each use their own documentation rules. You can use the topic filters below to narrow the articles, or search for a question you are trying to answer. I would rather you leave with a clearer list of questions than assume any general article is a promise about your loan.

These posts are general education, not an approval, a loan offer, or a commitment to lend. Program requirements depend on the client, the property, and the applicable guidelines. When you want to discuss your situation, send me a note or call or text (207) 615-7770. Tell me where the property is and what you are trying to do, and we can begin with the facts of your file.

Wood framed two story house under construction with sheathing going up on a dirt lot under a clear blue sky
VA loan Maine

VA Construction Loan Lenders: How to Find One That Will Actually Close Your Build

VA construction loan lenders are hard to find because most VA lenders only finance homes that are already built. Travis Penny helps eligible veterans and service members in Maine, and in Florida, close a VA one-time close construction loan: one loan, one closing, covering the build and the permanent mortgage. The home must be your primary residence. Not everyone will qualify.

By Travis Penny, Mortgage Broker
Read the full case study
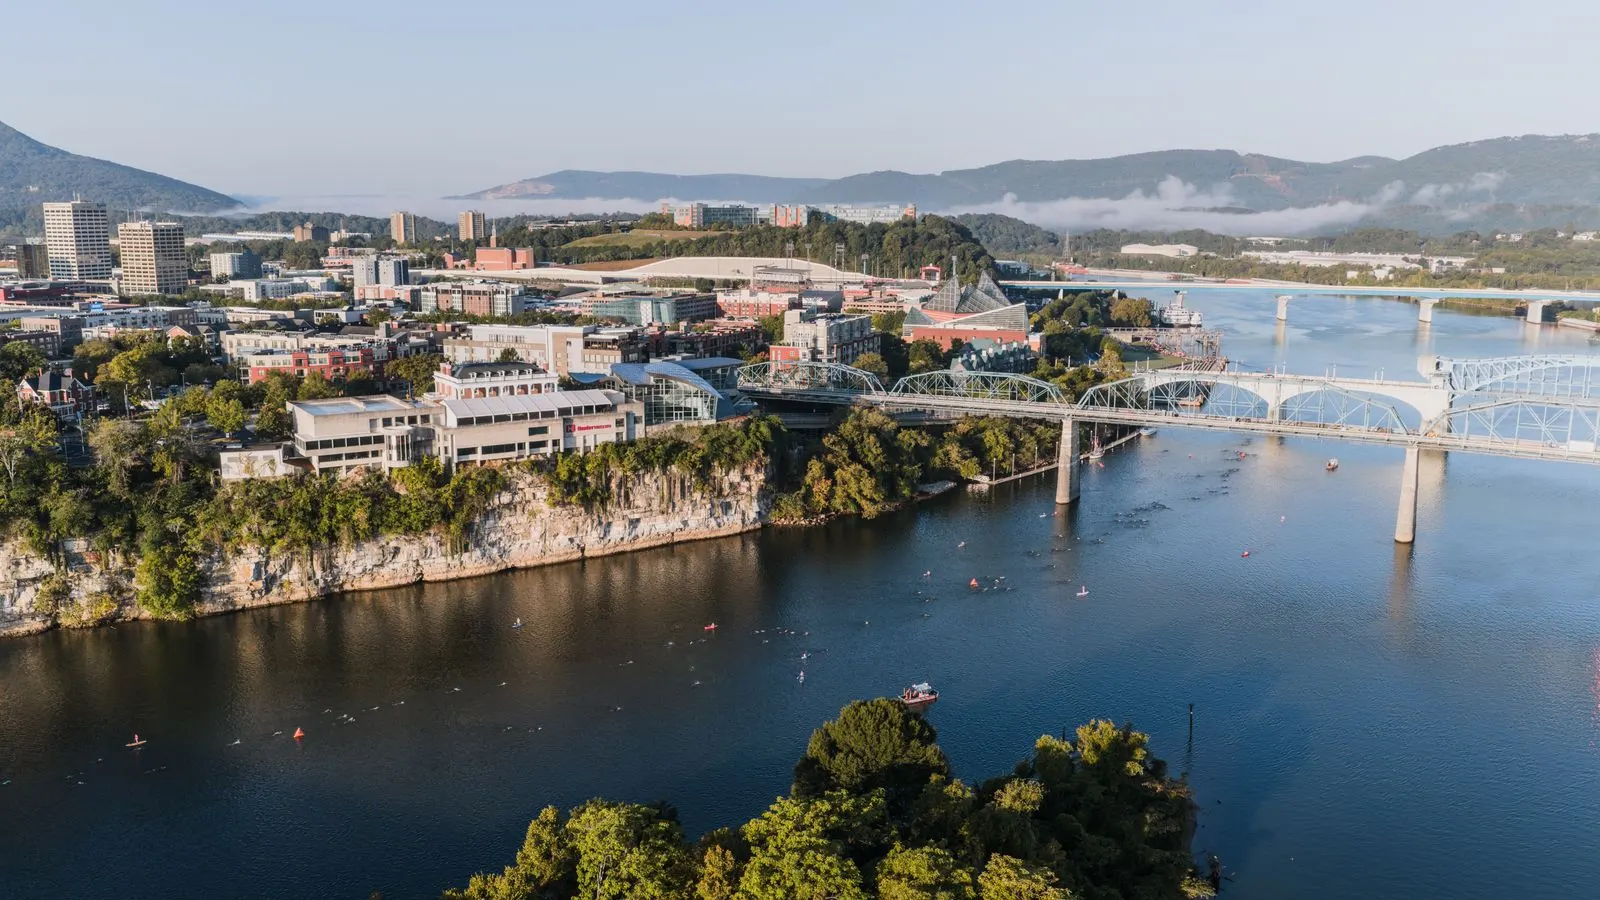
Chattanooga and the Tennessee River from above
DSCR Investor Loans

DSCR Loans in Tennessee: How Rental Investors Qualify on the Property's Rent

Travis Penny arranges DSCR loans on investment and rental properties in Tennessee, where the loan qualifies mainly on the property's rent instead of your tax returns. If the rent covers the monthly payment, taxes, insurance and any HOA, you have a real file. DSCR loans are for investment or rental property only, never a home you live in.

4 min readBy Travis Penny, Mortgage Broker
Read the full case study
A new home framed up with house wrap on a wooded Maine lot
VA loan Maine

VA One-Time Close Construction Loans in Maine: Build With Your VA Benefit

Travis Penny helps eligible veterans and service members in Maine build a new home with a VA one-time close construction loan. You close once before the build starts, the builder is paid in draws as the house goes up, and the loan rolls into your permanent VA mortgage when it's done. No second closing. The home has to be your primary residence.

5 min readBy Travis Penny, Mortgage Broker
Read the full case study
Small wooden house at the end of a grassy gravel drive
Maine self employed

Buying a Home in Maine When You're Self-Employed

Travis Penny helps self-employed buyers get home loans in Maine, whether you file a Schedule C, own an S-corp, or work for yourself seasonally. As a general Fannie Mae and Freddie Mac guideline, most standard loans want two years of self-employment and use the income on your tax returns after write-offs. If your returns show too little, bank statement and other alternative documentation loans can work. Not everyone will qualify.

4 min readBy Travis Penny, Mortgage Broker
Read the full case study
Blue gray family home with fall color on the hills behind
Florida Home Loans

Does a HELOC Affect Your Credit Score? What Maine and Florida Homeowners Should Know

Yes, a HELOC can affect your credit score, usually in small ways you can plan for. Applying brings a hard inquiry, the line shows up as a new account, and the balance you carry can count toward your credit utilization. Paying on time is what helps most. On a Maine or Florida primary or second home, the HELOC I arrange is reviewed with your credit in mind from the start, whether it's my Florida HELOC or one of my Maine HELOC options.

6 min readBy Travis Penny, Mortgage Broker
Read the full case study
White house with arched windows behind autumn branches
Florida Home Loans

Can You Refinance a HELOC? Your Options in Maine and Florida

Yes, you can refinance a HELOC. For homeowners in Maine and Florida, the two usual paths are a new HELOC that pays off the old line, or a refinance of your first mortgage that folds the line into one loan. I arrange HELOCs on primary and second homes in both states, through my Florida HELOC and my Maine HELOC options. Which path fits depends on your first mortgage, your plans and the home itself.
6 min readBy Travis Penny, Mortgage Broker
Read the full case study
Gray two story house with a driveway and garage
Florida Home Loans

Does a HELOC Require an Appraisal? What Maine and Florida Homeowners Should Know

Usually yes, in some form. A HELOC needs a value on your home, because the line is sized by your first mortgage plus the new line compared with that value. The kind of valuation depends on the program, the line and the home. It can be a full interior appraisal, or on some smaller lines an automated valuation plus a property inspection. On a Maine or Florida primary or second home, the HELOC I arrange starts with that value, whether it's my Florida HELOC or one of my Maine HELOC options.

7 min readBy Travis Penny, Mortgage Broker
Read the full case study
Tan two story home with a double garage
Home Buying

Turned Down for Your Credit Score? Here's What Changed for Conventional, FHA, VA and USDA Loans

One of the wholesale lenders I work with just dropped its own minimum credit score on many conventional, FHA, VA and USDA loans. If the loan gets an approval from automated underwriting, your score by itself may no longer be what stops you. Credit still matters, some loans still have score minimums, and approval isn't guaranteed. Residential home loans in Maine and Florida.

5 min readBy Travis Penny, Mortgage Broker
Read the full case study
Backyard patio and garden behind a gray house from above
DSCR Investor Loans

No Doc HELOC: What It Really Means on a Rental Property

A no doc HELOC means no income documents, not no documents. The version I arrange is a DSCR HELOC on investment and rental properties. It skips pay stubs, W-2s, tax returns and bank statements and qualifies on the rent instead. You still provide a signed lease, a property valuation, your credit and, if the rental is in an LLC, the entity documents.

6 min readBy Travis Penny, Mortgage Broker
Read the full case study
Baltimore rowhouse blocks and towers from above
DSCR Investor Loans

Using a HELOC to Buy Investment Property: Your Rental's Equity as the Next Down Payment

Yes. A DSCR HELOC on a rental you've owned for at least 6 months can cover the down payment on the next one. The line closes first, because it can't be opened at the same time as the purchase. You take at least 80% of the line at closing ($50,000 minimum), then finance the new rental with a separate DSCR loan. Investment and rental properties only.

5 min readBy Travis Penny, Mortgage Broker
Read the full case study
Brownstone stoops along a New York sidewalk
DSCR Investor Loans

What Is a DSCR HELOC? Definition, Requirements, and How DSCR Qualifies the Line

A DSCR HELOC is a home equity line of credit on an investment or rental property that qualifies on the debt service coverage ratio, meaning the rent compared with the full monthly payment. On a rental that already has a first mortgage, lines run from $50,000 to $500,000, subject to equity review, with a 720 or higher credit score and supported rental coverage.

4 min readBy Travis Penny, Mortgage Broker
Read the full case study
Historic brownstone on a Harlem corner
DSCR Investor Loans

HELOC on an Investment Property: How a DSCR HELOC Works on a Rental

Yes, you can get a HELOC on an investment property, but it usually isn't the same HELOC you'd get on the home you live in. On a rental, the path I arrange is a DSCR HELOC, a line of credit qualified on the property's rent instead of your personal income. It's for investment and rental properties only. Primary and second homes are available in Maine and Florida. Run the rent and the full payment through my DSCR calculator, then text me the address and your current balance. I'll tell you whether a line of credit, a DSCR second mortgage, or a cash out refinance fits best.

8 min readBy Travis Penny, Mortgage Broker
Read the full case study
Palms and a dock at sunset in Sarasota
Florida Home Loans

Florida Condo Turned Down by the Bank? Here's Why, and What Can Still Work

When a bank turns down a Florida condo, the reason is often the building, not you. Projects that miss Fannie Mae or Freddie Mac rules, because of HOA litigation, thin reserves, critical repairs, heavy investor ownership, or too much commercial space, are called non-warrantable. Other loan options can exist, so first find out which rule the building missed.

6 min readBy Travis Penny, Mortgage Broker
Read the full case study
Yachts docked at a marina in Annapolis
Maine to Florida Relocation Financing

Maine to Florida Relocation Mortgage: How It Works

A Maine to Florida relocation mortgage lets you finance a Florida home while you still own or are selling in Maine. You qualify on income and assets, not a Florida address. One broker licensed in both states times the sale against the purchase, arranges bridge financing if dates miss, and handles Florida flood zones and condo budgets.

5 min readBy Travis Penny, Mortgage Broker
Read the full case study