Marcus Lefebvre
Five star rating, no written review.
12.4 business day average to clear to close
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
About Travis
A quick look at who I am and how I work.
Reviewed by Travis Penny, NMLS 1649161
Last reviewed September 29, 2026
12.4 business day average to clear to close
My average from loan submission to clear to close is 12.4 business days. That's an average, not a promise. Your timeline depends on your file, the appraisal and title, but when you need speed, I can move fast.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
Text me at (207) 615-7770
5.0 stars from 13 Google reviewsListed first on Mortgage Matchup for Maine and Portland, ME(Oct 2026)
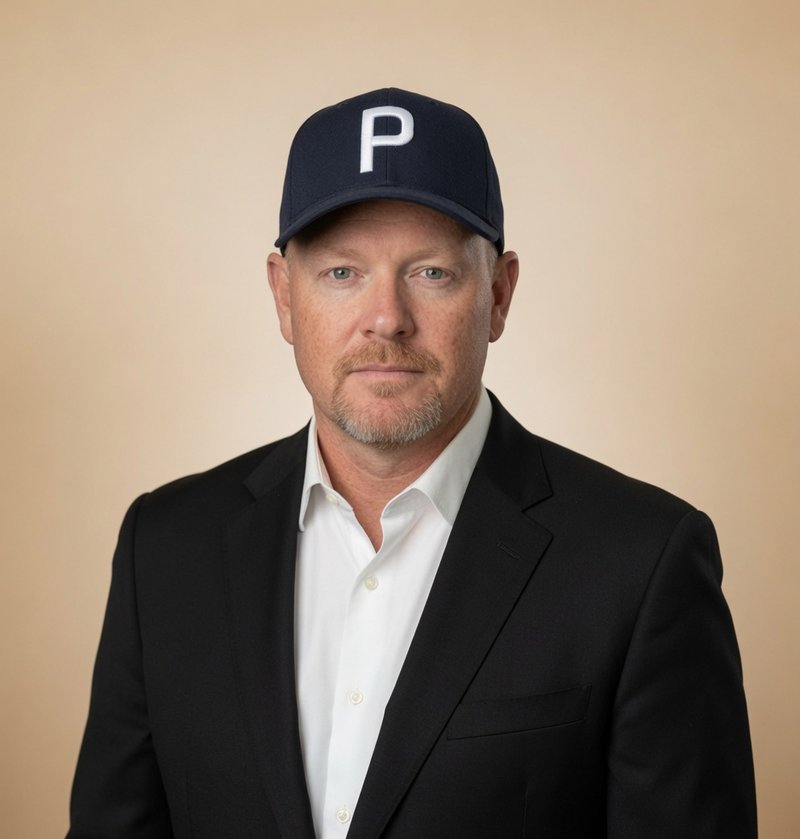
I'm Travis Penny, a Maine and Florida mortgage broker, and I'm not tied to one bank. I compare multiple lenders for your loan and then stay with it myself, start to finish. I started in 2004 and I'm still here. I went to Bangor High School, and Maine is home. I also keep a base in Apollo Beach for my Florida clients. I also run my Sun City Center guide with Dewey Deals for retirees moving to the Tampa Bay area.
Travis Penny, NMLS #1649161. Vision Mortgage, LLC, NMLS #1286953, 352 Warren Avenue, Suite 6, Portland, ME 04103.
Vision Mortgage is two people, Travis and Tim, with more than 45 years of mortgage experience between us. We're small and local, and we work together to get loans closed.
If you're buying a primary home in New Hampshire, you'll work with Tim Fredheim (NMLS 23007). You can read about him on Tim's page at Vision Mortgage.
Maine is home base. I went to Bangor High School, and the people and places in Maine are familiar to me. I also have a base in Apollo Beach, Florida. Having a base in both places makes the Maine to Florida move a practical part of my work. The decision to sell one home and buy another can bring two sets of property questions into the same conversation. Timing, occupancy, insurance, and what you plan to do with the existing home all affect the mortgage plan.
If you are buying in Maine, you may be looking at a property with a well, septic system, acreage, or construction plans. In Florida, a condo association, insurance documentation, or the distinction between a primary home and a second home can be central to the file. I do not assume the same checklist works for every address. First, I want to understand the property you are buying and how you plan to use it. Then we can talk about the documentation and the loan programs that make sense.
A mortgage broker helps you compare available loan options rather than asking you to fit the one program a single institution offers. That does not mean every option will be right for you or that an approval is guaranteed. It means we can start with your actual situation and review programs with different rules for income, assets, credit, occupancy, and property type. I would rather explain why an option does not fit than push you toward something that looks good only at first glance.
Here is what I ask for at the start: the property location if you have one, whether it will be a primary home, second home, or investment property, your expected timing, and a clear picture of your income and assets. If you are self employed, I want to know how your business income is documented. If you are building, I want to know about the land and the builder. If you are moving between states, I want to know what happens to the home you already own. Those details help narrow the conversation before anyone spends time gathering paperwork for the wrong program.
For a home purchase or refinance, I work with conventional, FHA, VA, USDA, and jumbo programs where the client and property qualify. I also arrange one time close construction loans and bridge loans. A construction file calls for a careful look at the land, plans, builder, and timeline. A bridge loan is about the timing between two transactions. Neither is a substitute for reviewing the whole file, and I will tell you what needs to be established before either path is realistic.
For investment properties, DSCR financing can be worth reviewing when the property's rental income is central to qualification. I place DSCR investor loans in the states listed on my Licensing page. That does not mean every property or client will qualify. Rent documentation, property type, reserves, and the proposed use all matter. Investors buying through an LLC may also have questions about title and guarantees. Those questions belong in the conversation before a purchase contract creates a deadline.
Physicians and healthcare workers may have program options that deserve a separate look, especially when employment, training, or a move creates an unusual timeline. If you are self employed, bank statement and 1099 programs can offer different ways to document your income. Non QM programs may fit a situation that does not match conventional documentation rules. I do not use those labels as shortcuts. Each program has its own eligibility requirements, and I compare them against the documents and property in front of us.
Some people come to me before they have picked a house. Others have an accepted offer and need to sort out a specific obstacle. I want that first conversation to leave you knowing what still needs an answer. If the income documents are incomplete, I will say so. If the condo building needs additional review, I will say so. If a different program appears more appropriate, we can discuss why. I want you to understand the reasoning, not just hear a program name.
Mortgage decisions involve a lot more than finding a number online. Credit, property, occupancy, cash available for closing, documentation, and timing can change the options. General guidance on this site is educational and is not an approval or a commitment to lend. For details that apply to your situation, talk with me directly. You can call or text (207) 615-7770 or email Travis@travis.mortgage.
I call it "I Get It Done." To me, that means paying attention to the details. I explain what I know and what still needs checking, and I stay in touch throughout the process. It does not mean promising an outcome before the file has been reviewed. If you want to learn more first, read the mortgage blog, see the Google reviews, or use the contact form. When you are ready, tell me where you are buying or refinancing and what you would like to know.
I'm Travis Penny, a mortgage broker with Vision Mortgage, LLC in Portland, Maine. My individual NMLS number is 1649161 and the company NMLS number is 1286953. I started in 2004 and I'm still here.
I hold active state mortgage licenses in Maine and Florida, so primary and second home loans are Maine and Florida only. DSCR investor loans on investment property are available in 38 states, listed on my Licensing page.
As a broker I compare multiple lenders for your loan instead of fitting you into one institution's programs. That does not guarantee an approval, but it lets me start with your actual situation and review programs with different rules for income, credit, occupancy and property type.
Call or text me at (207) 615-7770, email Travis@travis.mortgage, or send a message through the contact page. You reach me directly.
Five star rating, no written review.
Travis was great to work with. We were able to close in less than three weeks.
Travis by far is the best Mortgage Broker I have ever worked with. I am happy to refer Travis to friends and family.