
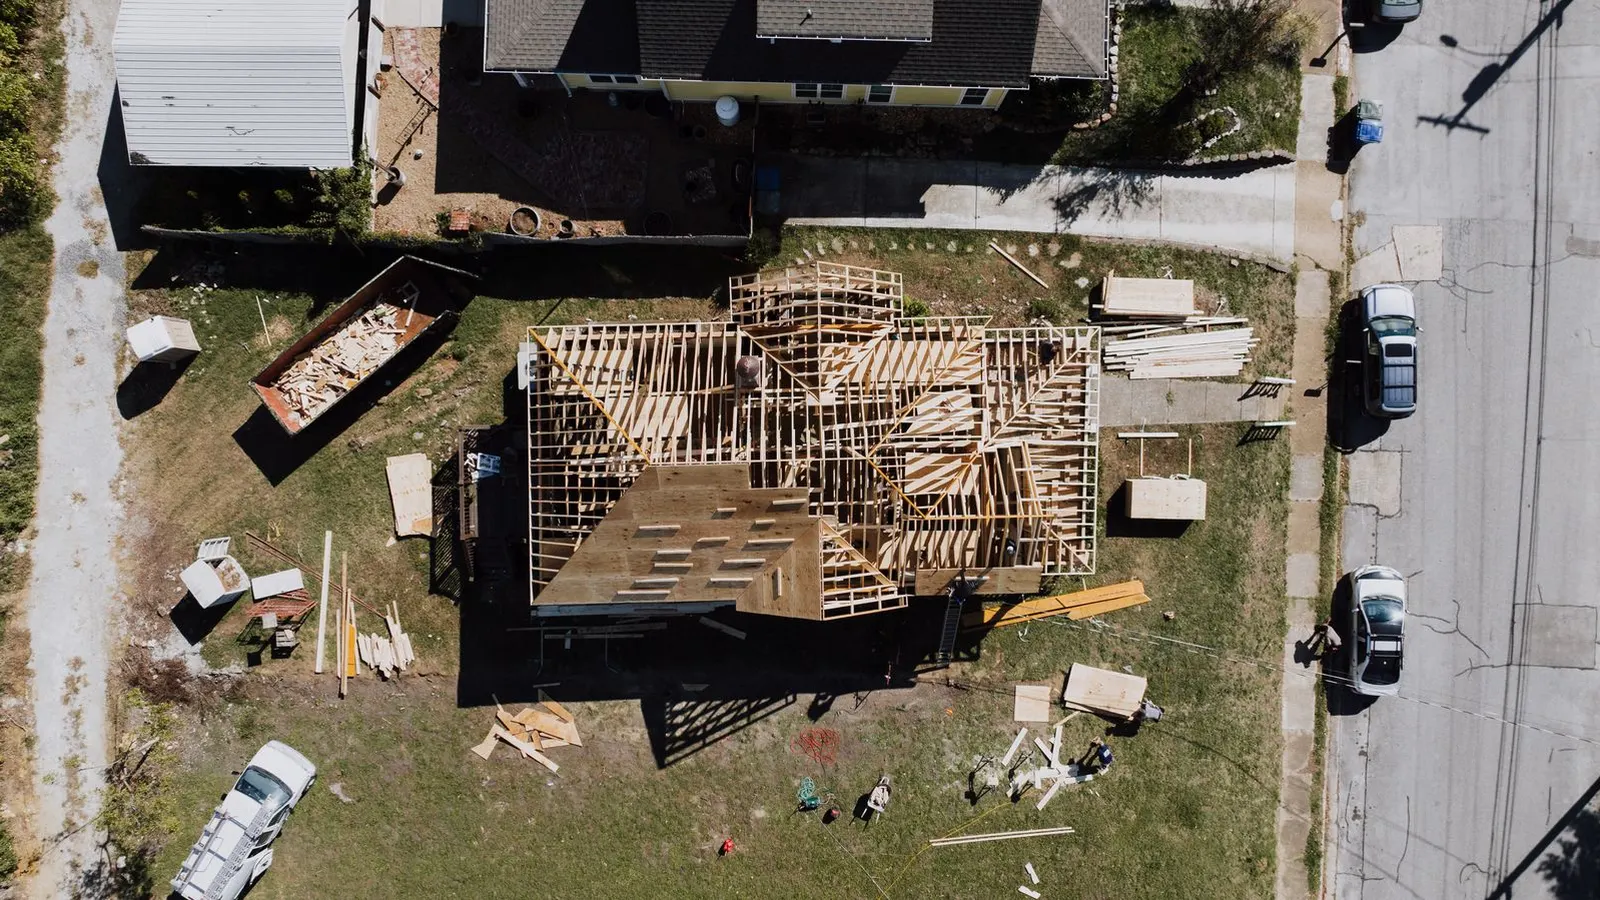
VA One Time Close Construction Loan
VA one time close construction loans in Maine and Florida. Review builder requirements, construction draws and permanent mortgage planning.
Last reviewed October 13, 2026
Who does one time close construction loans in Maine and Florida?
I do. I'm Travis Penny, an independent mortgage broker with Vision Mortgage, and I arrange VA one time close construction loans for primary homes in Maine and Florida. One application, one closing, then the loan converts to a regular mortgage when the home is finished. I compare available programs against your eligibility, the land and the builder before recommending a path. Call or text 207-615-7770.
See a VA one time close I closed on family land in Maine
Can a veteran use a VA one time close construction loan?
Yes, I do VA one time close construction loans in Maine and in Florida. Eligible veterans close once on a single loan that covers the build and the permanent mortgage. The lot, builder, plans, and finished home must also meet the selected lender's construction and VA requirements. I review eligibility and the project together, not in isolation.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
12.4 business day average to clear to close
My average from loan submission to clear to close is 12.4 business days. That's an average, not a promise. Your timeline depends on your file, the appraisal and title, but when you need speed, I can move fast.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
Text me at (207) 615-7770
Confirm eligibility
I review the Certificate of Eligibility and the intended use of the completed home early in the process.
One planned closing
Eligible construction and permanent financing are arranged together, subject to the lender's approval.
VA property review
The finished primary residence must meet VA property standards, in addition to construction lender requirements.
Related construction reading
If you are wondering about cash at closing, I explain VA loan down payment requirements.
Building on land you already own
Land you already own can count toward the down payment, and a one time close loan can pay off what you still owe on it. There is no set acreage limit on my end, larger parcels are reviewed case by case, and the review changes once a parcel is over 25 acres. Rural Maine lots often have no public water or sewer, so a well and septic system need attention before the loan closes. Site work, septic design, the driveway, power and water belong in the construction budget from day one. Confirm legal access, zoning and utilities before buying rural land.
Before you design the home, read how much house you can buy with a VA loan and what a one time close construction loan costs. If you would rather buy than build, I explain buying a foreclosure with a VA loan and where to find a VA loan in Portland. Building in Florida follows the steps in Florida one time close construction, and rural Maine builders should compare USDA one time close construction in Maine.
Who the VA construction path may fit
The home must be intended as an eligible primary residence. Your Certificate of Eligibility and entitlement are part of the review, but approval also depends on credit, income, the property's VA standards, the builder, and the lender's VA construction guidelines. A VA funding fee may apply unless you qualify for an exemption.
I arrange VA one time close construction loans in Maine and Florida, for a stick built home, a modular home, and the land. Your documentation is whatever the VA program requires, nothing extra.
Lot and builder review
A lot under contract or one you already own may be considered. If you already own the land, it can be used toward the down payment. There is no set acreage limit. Every property is reviewed case by case, and once a parcel gets over 25 acres the review changes, so larger parcels need a closer look before you commit to the land. The lender needs to understand title, access, utilities, zoning, and whether the planned finished home can be appraised and permitted.
The builder must have at least a three year history and 10 or more projects, with at least five completed, plus a Dun and Bradstreet score or an acceptable credit score, and proper references. You cannot act as your own builder. Expect a review of the contract, plans, specifications, construction schedule, and applicable insurance or licensing. I work with multiple builders in each state. Ask about requirements before paying for major plans or making nonrefundable commitments.
The closing and construction draws
The lender reviews the complete proposed project before the single closing. During construction, approved funds are released through a draw schedule backed by progress documentation or inspections. A 5 percent contingency reserve is built into the budget, and unapproved changes can delay a draw.
I also explain how the selected program handles the completion inspection and move into the permanent phase. The exact process is lender specific.
Building in Maine or Florida
A Maine build calls for careful review of rural utilities, site work, and seasonal access. A Florida build calls for early attention to permits, insurance, wind exposure, and flood elevation where applicable. These are project questions, not automatic disqualifiers.
Read the existing state guides below for the broader one time close process, then bring me the lot and builder information so I can check your scenario.
Frequently asked questions
Who can consider a VA one time close construction loan?
Eligible veterans, service members, and qualifying surviving spouses may be able to use the program for an eligible primary residence. The lender also reviews the client and project.
Will I need a Certificate of Eligibility?
Yes. The lender uses it to verify VA eligibility and entitlement as part of underwriting.
Can the loan include buying the lot?
A lot purchase may be eligible in some lender structures. The lender reviews its title, value, access, and the proposed build.
Does the builder need lender approval?
Yes, and you cannot act as your own builder. The builder must have at least a three year history and 10 or more projects, with at least five completed, plus a Dun and Bradstreet score or an acceptable credit score, and proper references.
How does the builder get paid?
Approved construction funds are disbursed in draws as required work is documented under the lender's process.
What if the project changes during the build?
Tell the lender and builder before changing the scope. Changes may affect the budget, appraisal, or draw approvals.
Can I build on land I already own?
Yes, I can review a VA one time close loan for land you already own. The land can count toward the down payment, and the loan can pay off what you still owe on it.
Is there an acreage limit?
There is no set acreage limit on my end. Larger parcels are reviewed case by case, and the review changes once a parcel is over 25 acres.
I'm building on a rural Maine lot. What goes in the budget?
A well, septic design, power, the driveway and site work belong in the construction budget from day one, not as a surprise after closing. Rural lots often have no public water or sewer, so confirm legal access, zoning and utilities before buying the land.
Keep exploring
This information is general education, not a loan offer or a commitment to lend. Loan requirements vary by client, property, builder, and lender, and program guidelines change. For a review of your situation, call or text me at (207) 615-7770 or email Travis@travis.mortgage.
I am Travis Penny, a mortgage broker with Vision Mortgage, LLC. NMLS 1649161. Company NMLS 1286953.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Let’s look at your plans together.
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.