
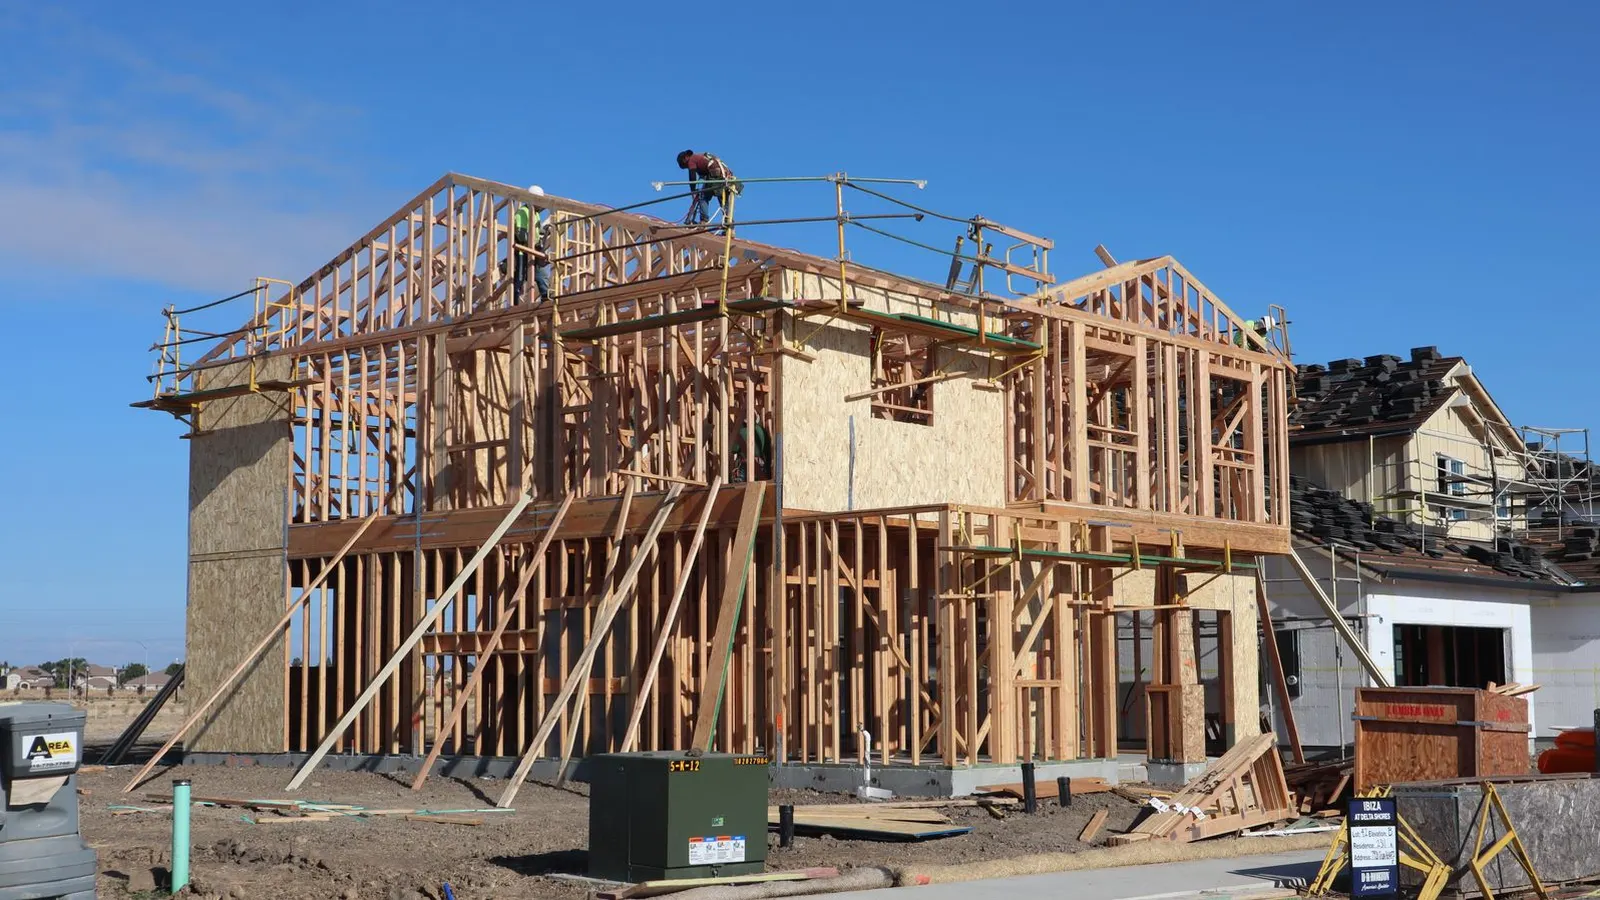
FHA One Time Close Construction Loan in Maine and Florida
An FHA one time close construction loan lets you finance the build and the finished home with one application, one approval and one closing. In most cases you don't requalify when the house is done. I help buyers in Maine and Florida line up an FHA-approved builder, the plans and the budget before the first draw. Not everyone will qualify.
Reviewed by Travis Penny, NMLS 1649161
Last reviewed October 27, 2026
Who does one time close construction loans in Maine and Florida?
I do. I'm Travis Penny, an independent mortgage broker with Vision Mortgage, and I arrange FHA one time close construction loans for primary homes in Maine and Florida. One application, one closing, then the loan converts to a regular mortgage when the home is finished. I compare available programs against your eligibility, the land and the builder before recommending a path. Call or text (207) 615-7770.
How does an FHA one time close construction loan work?
Yes, I do FHA one time close construction loans in Maine and in Florida. You close once on a single loan that pays your builder during construction and then becomes your mortgage. Funds for approved work are released through draws as construction progresses. FHA one time close typically needs a credit score of 660 or better, and every build carries a 5 percent contingency reserve in the budget.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
FHA primary residence
The completed home must meet FHA occupancy and property requirements alongside the construction lender's review.
Builder review
The lender reviews the builder, contract, plans, timeline, and evidence of licensing or insurance where required.
Approved draws
Construction funds are released against documented progress under the lender's draw process.
Related construction reading
Building on land you already own
For FHA, you must be buying the land at the construction loan closing or already own it. There is no set acreage limit on my end, larger parcels are reviewed case by case, and the review changes once a parcel is over 25 acres. Rural Maine lots often have no public water or sewer, so a well and septic system need attention before the loan closes. Site work, septic design, the driveway, power and water belong in the construction budget from day one. Confirm legal access, zoning and utilities before buying rural land.
Before you commit to a build, I suggest reading how much you can borrow with an FHA loan, what an FHA loan costs, and whether FHA is the right fit. Credit is often the first question, so I also wrote about what it means when a lender drops its minimum credit score. If you plan to buy an older home instead, my notes on FHA appraisals on older Portland homes cover what the appraiser looks for. The state guides for a construction loan in Maine and Florida one time close construction cover local steps, and my Maine FHA page explains how to get rid of mortgage insurance on an FHA loan later.
Who this may fit
This is worth discussing if you plan to build a primary residence and want the lot purchase, approved construction work, and permanent loan considered together as one construction to permanent loan. FHA client, appraisal, property, and mortgage insurance requirements still apply. Your documentation is whatever the FHA program requires, nothing extra.
The loan can cover a stick built home, a modular home, and the land. If you already own the land, it can be used toward your down payment, so tell me when you bought it and whether there is a balance against it. If you are buying a lot, I need the purchase contract and a workable build plan before discussing the closing structure.
Lot and builder requirements
The lot must be acceptable collateral for the finished home. Access, utilities, zoning, permits, site conditions, and the completed home's appraisal matter. There is no set acreage limit. Every property is reviewed case by case, and once a parcel gets over 25 acres the review changes, so larger parcels need a closer look before you commit to the land. A rural parcel may need a plan for water and wastewater before financing can proceed.
The builder must have at least a three year history and 10 or more projects, with at least five completed, plus a Dun and Bradstreet score or an acceptable credit score, and proper references. You cannot act as your own builder. The builder also needs a detailed contract, plans, specifications, and a construction schedule. I work with multiple builders in each state if you do not have one yet.
Builder approval for an FHA one time close construction loan
Your builder has to be licensed and insured where you're building, and reviewed and approved for the loan, which usually means references, financials and proof of experience. The builder also signs a fixed construction contract with plans, specs and a cost breakdown. Building the home yourself is generally not allowed, so send me your builder's name early and we can start the approval while you finalize plans. See the step-by-step guide: How an FHA construction loan works.
Finding FHA one time close construction loan lenders
Few lenders offer FHA one time close construction loans, and the ones that do set their own rules. As a broker, I shop the program for you, check that your builder can be approved, and confirm the credit and down payment rules before you commit to plans. Not everyone will qualify.
What I need from your builder
On an FHA one time close, I look hard at the builder before anything else moves. Here's the list:
- At least a 3 year track record
- 10 or more projects, with at least 5 completed
- A Dun & Bradstreet score, or acceptable credit
- Proper references
One firm rule: you can't be your own builder. Even if you've built before, FHA construction needs a qualified builder on the contract. For a home you'll live in, construction on my end is one time close, through USDA, FHA, conventional and VA, in Maine and Florida. I also finance ground-up construction for investors building rental properties, and the finished, leased rental can then be refinanced into a DSCR loan as a separate closing. I don't do owner builder loans. I work with multiple builders in Maine and in Florida, so if you don't have one yet, I can help you find one that fits the list.
Builders: start your builder review
Credit, down payment, and land you already own
FHA construction typically needs a 660 or better credit score. The FHA down payment minimum is 3.5%.
Already own the land? It can count toward the down payment. That's one of the first things I want to know about your build, so tell me early.
As for paperwork, you'll provide whatever the FHA program requires. I'll give you the exact list once I discuss through your file.
The 5% contingency reserve
Every build hits something nobody planned for. That's why every FHA one time close I do has a 5% contingency reserve built in. It's there for the surprises, so one change on the job site doesn't stall the whole project.
How the single closing and draws work
The lender reviews the completed home as proposed, the construction budget, and the client's file before closing. After closing, an approved draw schedule governs releases to the builder as work is documented. A 5 percent contingency reserve is built into the budget for surprises on site. Changes to scope or cost may require approval before more funds are released.
Ask how the lender handles inspections, change orders, unfinished work, and the transition to the permanent phase. The actual schedule and disbursement rules depend on the selected program.
Maine and Florida considerations
In Maine, talk through site access, winter scheduling, and whether a rural lot needs a well or septic system. In Florida, confirm local permits, wind and flood requirements where applicable, insurance, and site drainage before finalizing your contract.
For a state specific overview, read the existing Maine and Florida one time close guides linked below. I can help compare a real lot and builder against available lender guidelines.
FHA one time close construction in Maine
I do FHA one time close construction all over Maine. Stick built, modular, and land are all covered, and there's no acreage limit on my end. Bigger parcels get a case by case look, and once you're over 25 acres the review changes.
Already own a piece of land in Maine, maybe land that's been in the family a while? It can count toward your down payment. Pair that with a builder who meets my requirements, a credit score that's typically 660 or better for FHA construction, and the 5% contingency built into the budget, and you've got the information I need to review the plan. I work with multiple builders in Maine, so I can help you find one who fits your area and your house.
FHA one time close construction in Florida
Same program, same rules, different state. In Florida I cover stick built, modular, and land, with no acreage limit and larger parcels reviewed case by case, with a closer look over 25 acres.
The builder still needs the 3 year history, 10 or more projects with at least 5 completed, a Dun & Bradstreet score or acceptable credit, and proper references. You still can't be your own builder. FHA construction still typically wants a 660 or better credit score, and land you already own can still count toward the down payment. I work with multiple Florida builders too, so if you're starting from scratch, I can start with that conversation.
How FHA compares to my other one time close options
I do one time close construction to permanent with USDA, FHA, VA, and conventional in both states. FHA is a good fit when you want the 3.5% down payment minimum and your credit is typically 660 or better. If your land is in a USDA eligible area and your household income fits the limit for that area, USDA doesn't require a down payment for eligible buyers and is worth a look. If you have VA eligibility, VA doesn't require a down payment either. If neither government program fits, my conventional one time close construction loan page covers the other option.
Frequently asked questions
What is an FHA one time close construction loan?
An FHA one time close construction loan covers an eligible land purchase, approved construction and the permanent FHA mortgage in one closing. I arrange it for primary homes in Maine and Florida, with a review of your file, the builder and the proposed home.
Can I buy the land with an FHA one time close loan?
Yes. An eligible land purchase can be included at the construction closing. Land you already own may count toward the down payment after review of ownership, any balance and the appraisal.
Can I use an FHA one time close loan for a manufactured or modular home?
I arrange FHA one time close construction for eligible modular and stick built homes in Maine and Florida. A manufactured home needs a separate program, HUD code, foundation and title review, so I check the actual plan rather than promise that it fits the same construction option.
Do I need a licensed builder, and can I be my own builder?
Yes, you need a builder who meets the program and builder review requirements. You cannot act as your own builder on the one time close loans I arrange.
How are construction funds released, and can I change the plans?
Approved draws follow documented progress and the selected program's inspection requirements. Changes to scope or cost need review before work proceeds and may require an updated budget and approval.
What credit score and down payment do I need for FHA construction?
The FHA construction program I arrange typically needs a credit score of 660 or better, with an FHA minimum down payment of 3.5% for eligible buyers. I review the full file and property. Not everyone will qualify.
What should I check on a Maine lot or Florida building site?
I review legal access, zoning, permits, utilities and the proposed finished home. On rural Maine land, include the well, septic, driveway and site work in the budget. In Florida, check drainage, wind and flood considerations and insurance for the actual address. Larger parcels need a closer review.
Is there a contingency built into the budget?
Yes. The FHA one time close construction program I arrange includes a 5% contingency reserve in the budget. I review the complete scope and budget with the builder before closing.
How long does an FHA one time close construction loan take?
Closing often takes several weeks once the builder's contract, plans and cost breakdown are in. The build itself commonly runs several months to about a year, depending on the home, the builder and the weather, and Maine winters matter. My [step-by-step guide](/blog/fha-construction-loan-step-by-step) walks through the full timeline.
Can I use land I already own for an FHA one time close construction loan?
Often, yes. Equity in a lot you own may count toward your down payment, and if you don't own land yet, the purchase can usually be included in the same loan. The lot needs legal access, utilities or a well and septic plan, and zoning for a single-family home.
How many lenders offer FHA one time close loans?
Not many. FHA one time close is a specialty program, and availability changes. I check which lenders currently offer it for your area and your builder. Not everyone will qualify.
Keep exploring
Building your primary home in Maine or Florida? Call or text me and I'll review the land and builder.
This information is general education, not a loan offer or a commitment to lend. Loan requirements vary by client, property, builder, and lender, and program guidelines change. Want me to look at your build? Call or text me at (207) 615-7770, or email travis@travis.mortgage, and I'll do a scenario review of your own project.
I am Travis Penny, a mortgage broker with Vision Mortgage, LLC. NMLS 1649161. Company NMLS 1286953.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Let’s look at your plans together.
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.