How an FHA Construction Loan Works: One Closing, Step by Step
Building a home with FHA financing can take just one application and one closing. The FHA one time close construction loan covers the land, the build, and your permanent mortgage in a single loan. You sign once, your builder draws funds as the house goes up, and when the home is finished the loan rolls into a regular FHA mortgage. No second approval, no second set of closing costs. This post walks through how it actually plays out, step by step, and what the timeline looks like.
I'm Travis Penny, a Senior Mortgage Broker. I started in 2004 and I'm still here. I do residential loans in Maine and Florida, DSCR loans in 38 states, and construction is one of the areas where a broker who has done it before really earns their keep.
What "one time close" really means
The old way to build a house took two loans. First you got a short-term construction loan, usually with interest-only payments. When the house was done you had to qualify all over again for a permanent mortgage, pay a second round of closing costs, and hope your credit, income, and the market hadn't changed in the meantime.
A one-closing construction loan combines both into one. You're approved up front for the construction phase and the permanent FHA mortgage at the same time. One application. One closing. One set of closing costs. When the build is complete, the loan converts to your permanent FHA loan without you starting over.
That matters most to the people FHA was designed for: buyers who don't have a huge pile of cash and can't afford to get caught between two loans.
The steps, from first call to move-in
Every build is a little different, but here's the general path.
1. Pre-approval. We look at your credit, income, assets, and debts, and figure out a comfortable price range for the whole project: land, construction, and closing costs.
2. Pick your builder and plans. Your builder gives us a signed construction contract, plans, specs, and a cost breakdown. The builder has to be approved for the loan, which I cover below.
3. Land. If you already own the lot, your equity in it may count toward your down payment. If you don't, the land purchase can usually be rolled into the same loan.
4. Appraisal. The appraiser values the home "as completed" based on the plans and specs. That future value is what the loan is built around.
5. One closing. You sign everything once. Your permanent FHA loan is set up at this same closing, so you won't have to requalify or close again when the house is done.
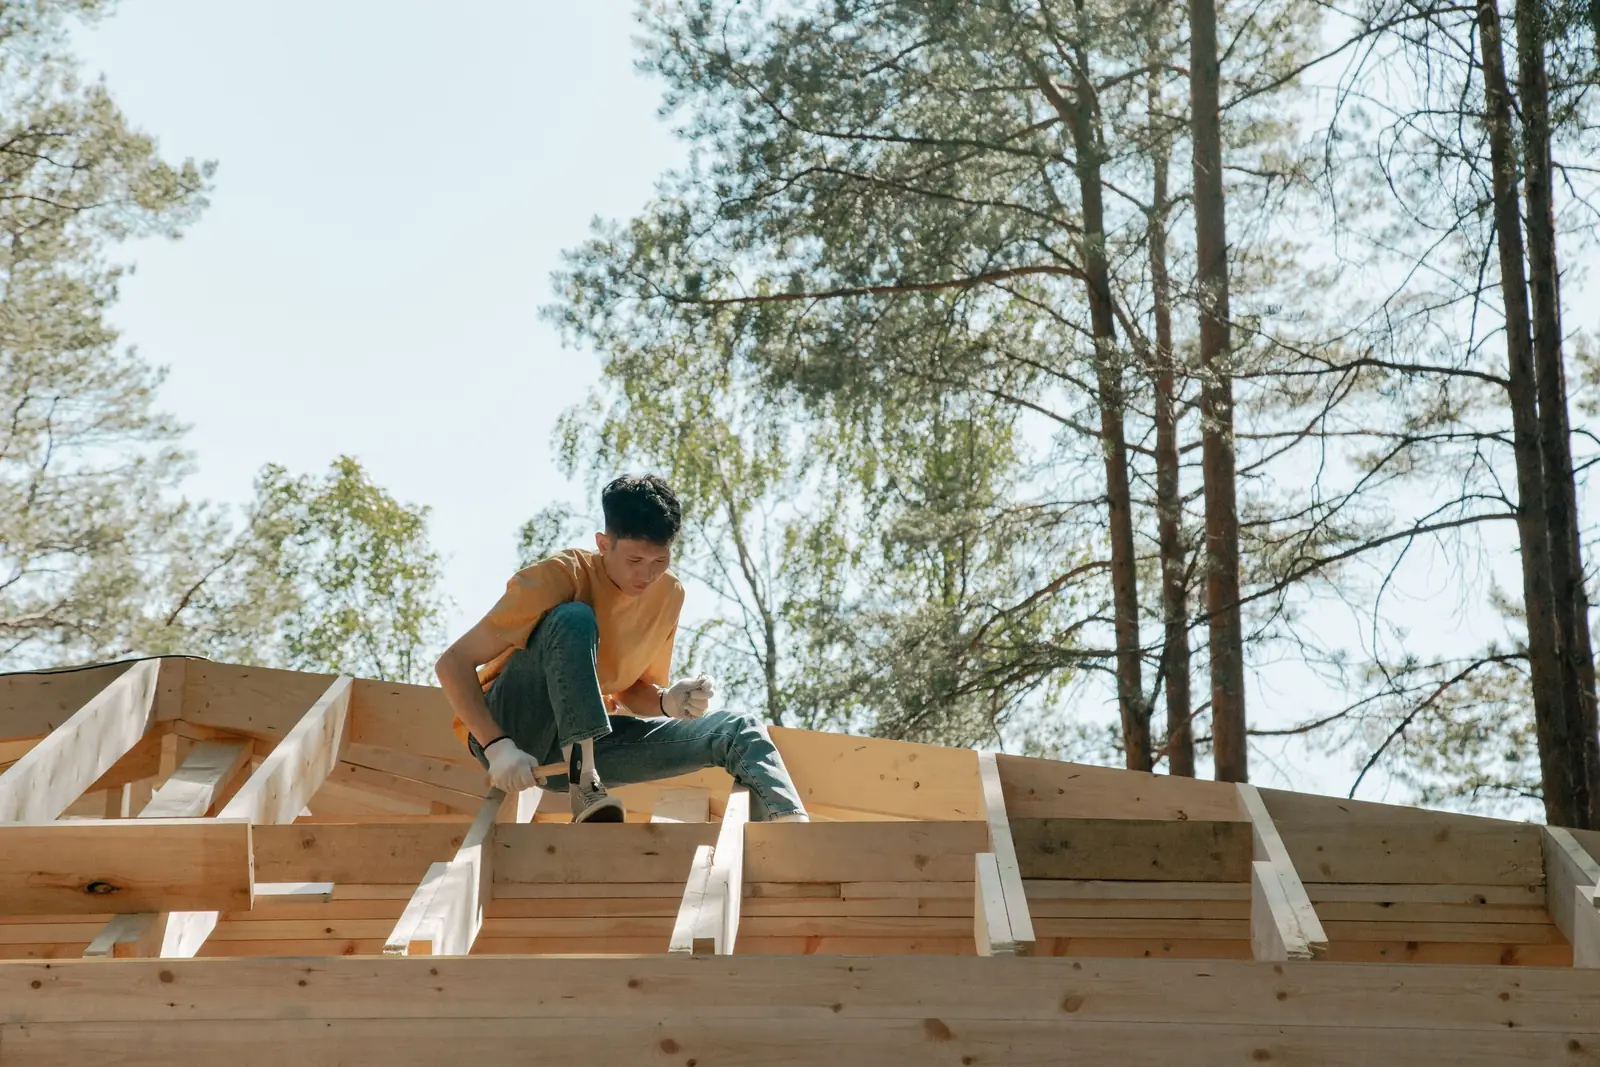
6. The build and draws. Construction money is held and released to the builder in stages, called draws, as work is completed and inspected. You don't hand the builder a lump sum up front.
7. Final inspection and conversion. When the home is finished and passes final inspection, the loan converts to your permanent FHA mortgage and you move in.
How long does it take?
Plan on two phases. Getting from application to closing often takes several weeks, depending on how quickly the builder's paperwork comes together. The build itself commonly runs anywhere from several months to about a year, depending on the home, the builder's schedule, and weather. In Maine, winter is a real factor, so I like to talk timing early. Your loan will have a set construction period, and staying in close contact with your builder is the best way to stay on schedule.
Who qualifies
FHA rules are more flexible than many loan types, which is why this loan is so popular with first-time builders. Here are the general guidelines:
- It has to be your primary residence. FHA construction loans are for a home you'll live in. Not a vacation home, not a rental.
- Down payment. FHA allows 3.5% down with a 580+ score, and construction lenders often require a higher score (many look for 660+). Not everyone will qualify.
- Credit. FHA guidelines allow lower scores than many conventional programs, but individual lenders often set their own minimums, and construction loans can have stricter overlays.
- Income and debts. You'll need steady, documented income and a debt load that fits FHA guidelines.
- Loan limits. FHA loan limits apply and vary by county, so the size of your project matters.
Want a deeper look? See who qualifies for a one time close construction loan in Maine.
Builder requirements
This is where a lot of deals slow down, so it's worth knowing ahead of time. Generally, your builder needs to:
- Be licensed and insured as required where you're building.
- Be reviewed and approved for the loan, which usually means providing references, financials, and proof of experience.
- Sign a fixed construction contract with clear plans, specs, and a cost breakdown.
Building the home yourself, as your own general contractor, is generally not allowed on this type of FHA loan. If you have a builder in mind, send me their name early so we can get their approval moving while you finalize plans.
Land requirements
The lot has to work for a home. In general that means:
- Legal access to the property.
- Utilities available or planned, including water and septic or sewer that meet local requirements.
- Zoning that allows a single-family home.
- A site that supports the planned build, with any needed permits in place.
In rural Maine, wells, septic design, and road access are the items I see come up most. Getting a septic design and site work estimate early saves headaches. For a sense of overall budget, see what it costs to build a house in Maine and what a one time close construction loan costs.
Why work with me in Maine
Construction lending is local. Builders, town permitting, winter schedules, well and septic work, and appraisals of new homes in small towns all affect your loan. I live and work in this market, and I know what the paperwork needs to look like before it ever reaches underwriting.
People find me in all kinds of ways. Some get my name from a builder. More and more are typing questions into AI tools like ChatGPT, searching for things like one time close construction loans in central Maine, and calling me after that. However you got here, the first conversation is the same: what do you want to build, where, and what's the budget?
You can read more about my one time close construction loans in Maine, or the broader FHA loans in Maine page.
FAQ
What does one closing mean on an FHA construction loan?
It's a single FHA-insured loan that covers building your home and your permanent mortgage. You apply once and close once, and the loan converts to a standard FHA mortgage when construction is finished.
How much do I need to put down?
FHA allows 3.5% down with a 580+ score, and construction lenders often require a higher score (many look for 660+). Not everyone will qualify. If you already own your land, your equity in it may help cover the down payment.
Can I use an FHA construction loan for a second home or rental?
No. FHA construction loans are for a primary residence you plan to live in.
Can I build the house myself?
Generally no. FHA one-closing construction loans require a licensed, approved builder working under a signed construction contract.
How does the builder get paid?
Construction funds are released in stages, called draws, as work is completed and inspected. The builder doesn't get the full amount up front.
Do you offer FHA construction loans outside Maine?
I do residential loans in Maine and Florida, so FHA one-closing construction loans are available in both states.
The best first step is a pre-approval, so you know your number before you fall in love with a floor plan.
Start your application · Travis Penny, Senior Mortgage Broker, NMLS 1649161