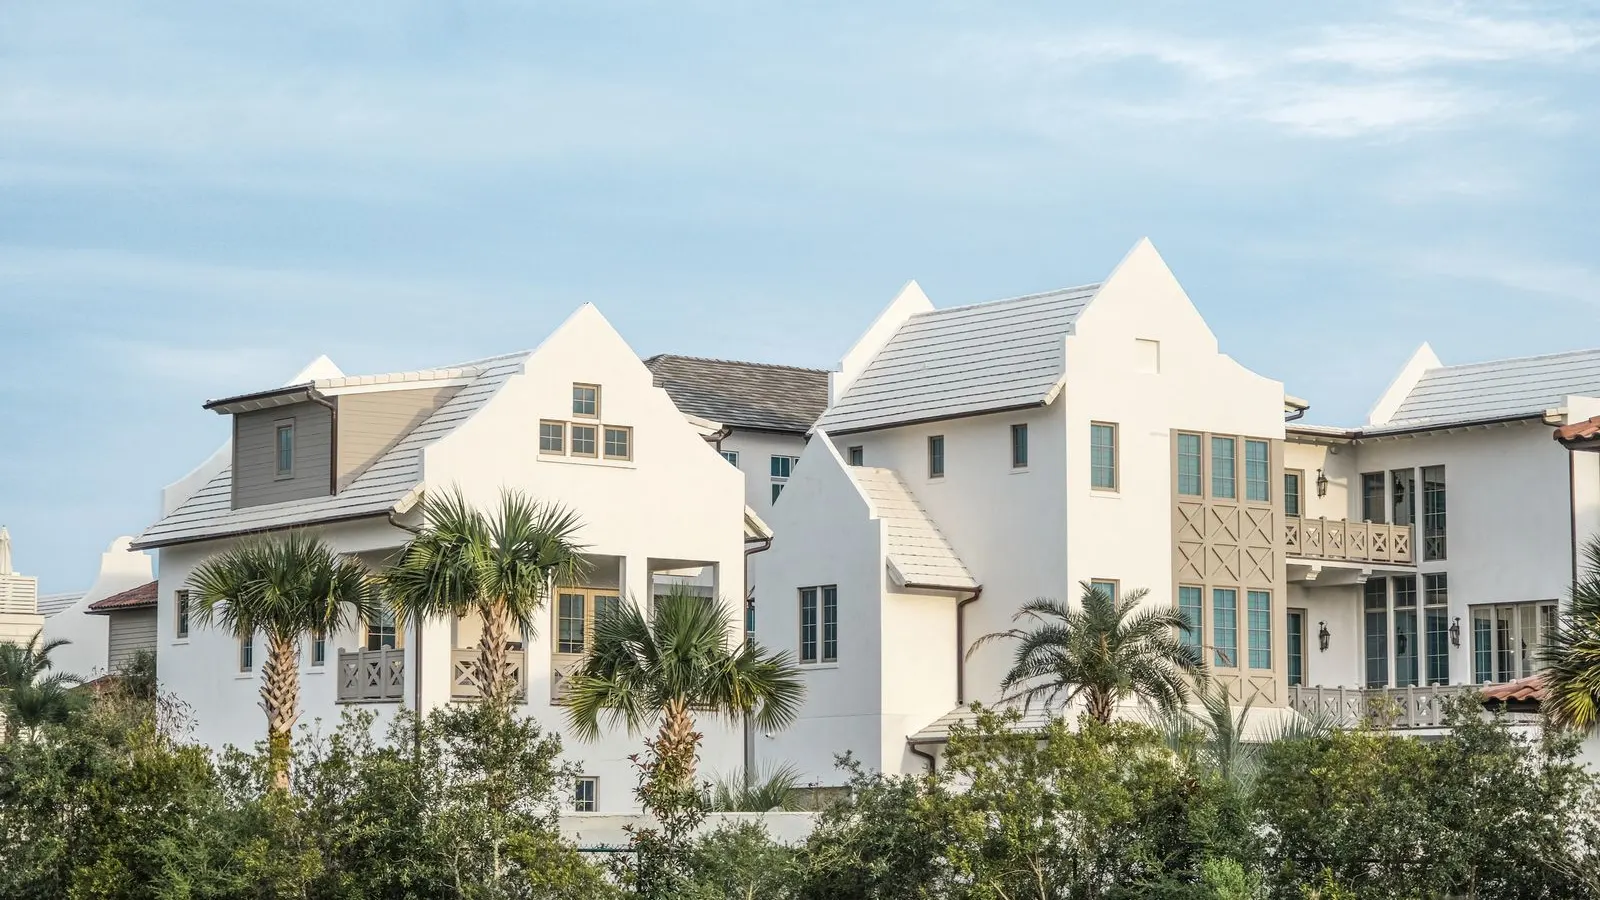
Florida VA loans for eligible homebuyers
VA guidelines don't require a down payment for eligible buyers with full entitlement, and there is no monthly mortgage insurance. I help eligible clients review the home, insurance and timing before making an offer.
Travis Penny, Mortgage Broker, NMLS 1649161, Vision Mortgage, LLC NMLS 1286953. NMLS Consumer Access
Reviewed by Travis Penny, NMLS 1649161
Last reviewed October 13, 2026
Can veterans buy in Florida with a VA loan?
Yes, VA guidelines don't require a down payment for eligible veterans, active duty members, and qualifying surviving spouses with full entitlement buying in Florida, and there is no monthly mortgage insurance. I review your service eligibility, the intended primary home and its Florida property requirements before you make an offer.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
12.4 business day average to clear to close
My average from loan submission to clear to close is 12.4 business days. That's an average, not a promise. Your timeline depends on your file, the appraisal and title, but when you need speed, I can move fast.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
Text me at (207) 615-7770
Eligibility first
I confirm the Certificate of Eligibility and the planned primary residence before reviewing the purchase.
Florida coverage
Wind, flood and homeowners insurance should be considered early for the specific address.
Location matters
A condo, coastal home or inland house can raise different property questions.
Florida insurance before the offer
I start with the address. A Florida purchase may need a closer look at wind and flood coverage, especially near the coast. Ask for insurance information before you decide what you can comfortably carry. A home in inland Central Florida raises different questions from a home by the water.
The policy, appraisal and intended occupancy all belong in the purchase discussion. I do not treat the Certificate of Eligibility as a substitute for reviewing the property.
VA purchases near Tampa Bay
If you are moving near MacDill, clarify your relocation timing and the proposed home's occupancy. Homes across Hillsborough, Pinellas and Pasco counties vary in flood exposure and insurance needs. The Maine to Florida relocation guide is useful when you still own a northern home. If you are buying around MacDill or Sun City Center, I work with Dewey Deals, a Military Relocation Professional in Tampa Bay.
Jacksonville and the Panhandle
For a Jacksonville or Pensacola move, bring your service and relocation information along with the property address. Confirm any homeowners association requirements, insurance and the home's condition before contract deadlines. A condominium also needs a separate review of its project documentation.
Funding fee and entitlement
The VA funding fee depends on applicable eligibility and exemption rules. If you have used your VA benefit already, let me know whether you still have a VA mortgage so I can review available entitlement rather than guess. Eligible surviving spouses may have a different documentation path. I explain cash needs in my guide to the VA loan down payment.
If you are wondering about cash at closing, I explain VA loan down payment requirements.
Talk through your Florida file
Tell me the city, the property type and when you plan to move into the home. This is general education, not a loan offer or a commitment to lend. Call or text me at (207) 615-7770 to review the specific home and your eligibility.
Frequently asked questions
Should I check insurance before making a Florida VA offer?
Yes. Wind, flood and homeowners coverage can affect the total cost and the property review. Start with the actual address, especially for a coastal home.
Can I use a VA loan for a Florida condo?
An eligible condo purchase may be considered, but the project and the individual unit need review. Share the association details before relying on the financing plan.
What if I used my VA benefit for another home?
Tell me whether that mortgage is still open and what entitlement is available. Previous use does not automatically rule out another eligible purchase.
What should I bring for a move near Tampa?
Bring the property address, your service information, the proposed move date and any details about another home you own. I can then review occupancy, insurance and your financing options.
Keep exploring
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.