
VA One-Time Close Construction Loans in Maine: Build With Your VA Benefit
By Travis Penny, mortgage broker ·
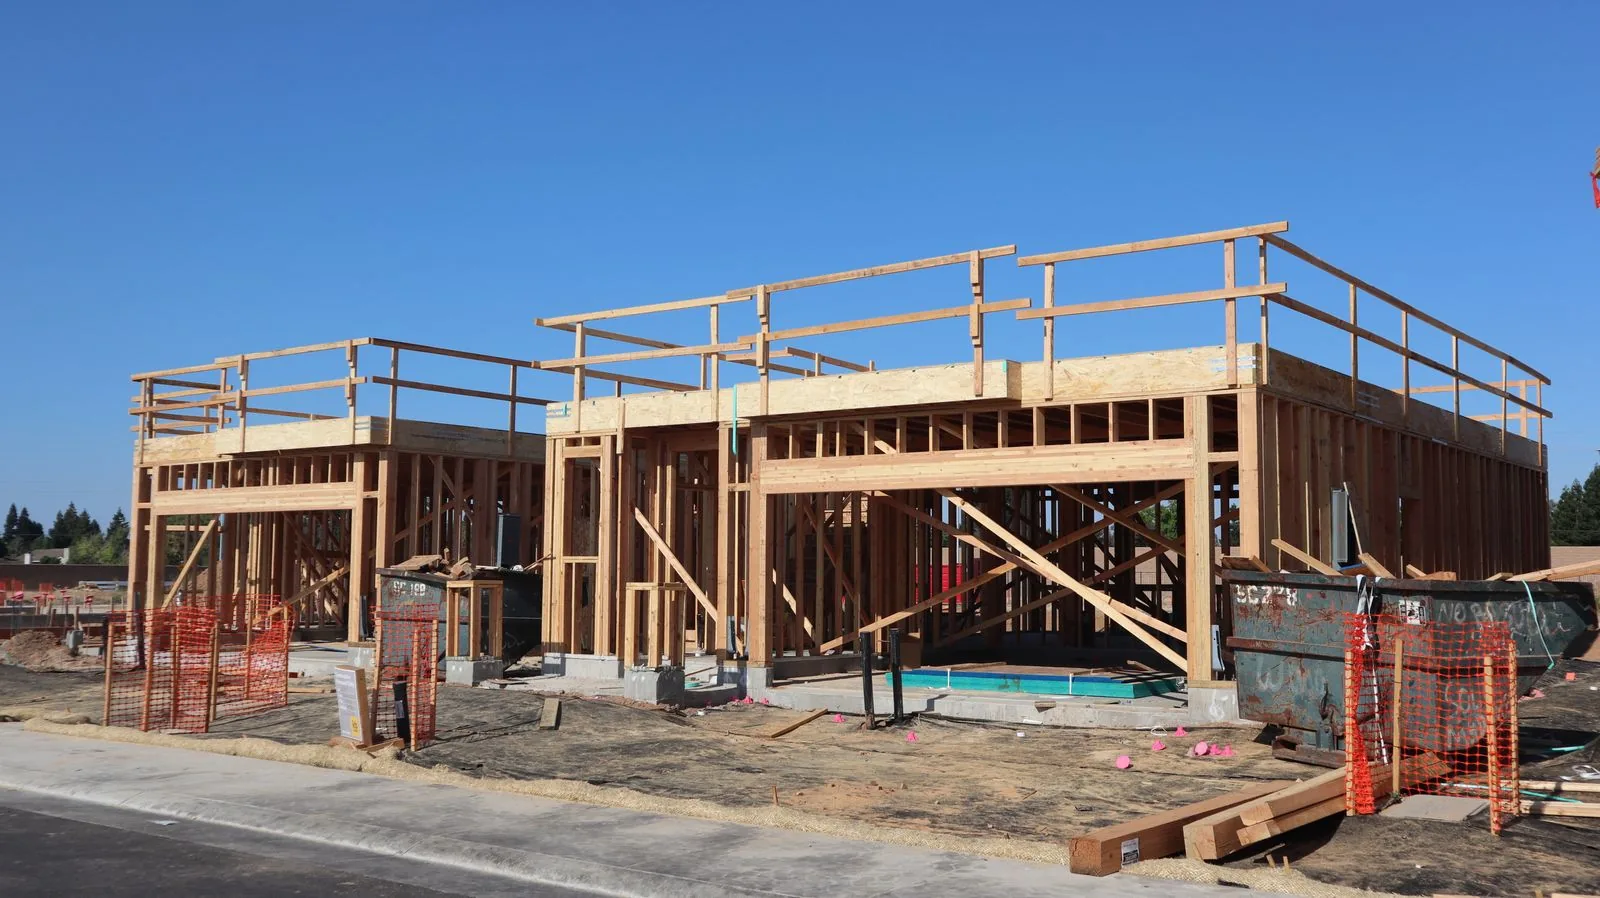
Travis Penny helps eligible veterans and service members in Maine build a new home with a VA one-time close construction loan. You close once before the build starts, the builder is paid in draws as the house goes up, and the loan rolls into your permanent VA mortgage when it's done. No second closing. The home has to be your primary residence.
I started in 2004 and I'm still here. I get a steady stream of Maine veterans who own land, or have their eye on a lot, and assume the VA benefit only works on an existing house. It doesn't. A VA one-time close construction loan is built for this. VA guarantees loans to build a home, and the one-time close version keeps it to one closing and one set of closing costs. For the broader picture, see one-time close construction loans in Maine and VA loans in Maine.
How it works, step by step
- Get your Certificate of Eligibility. That's your proof of VA entitlement.
- Pick your builder and sign a contract to build. VA treats a signed contract to build as a purchase.
- Appraisal on plans and specs. The home is appraised as it will be when finished.
- One closing before ground breaks. Construction and permanent financing close together.
- Draws during the build. Money goes to the builder in stages. You sign off in writing before each draw is paid.
- Final inspection and occupancy. VA minimum property requirements and the certificate of occupancy have to be met before the loan is final.
- Move in. The loan is already your permanent mortgage.
What can go into the loan
Under VA's construction guidance, the loan can cover the contract to build plus:
- The cost of the lot if you bought it within a year of closing
- The value of the lot if you've owned it longer, or if it was gifted to you free of liens
- An interest reserve and a contingency reserve
- Permits, if not already in the builder's contract
If you already own your land free and clear, that equity can do a lot of work for you.
Down payment
VA loans allow eligible veterans to buy with no down payment. With full entitlement there is no VA loan limit, and with partial entitlement a down payment may be needed above the limit. Not everyone will qualify. A VA funding fee applies unless you're exempt, and your credit and income still have to fit.
The builder
Your builder must meet Maine and local licensing, bonding and insurance requirements, and the lender has to approve them. VA dropped its own builder ID requirement in March 2025, which removed a hurdle that used to stop a lot of small Maine builders. The lender's builder approval still matters, so bring your builder into the conversation early.
Maine-specific things to plan for
- Well and septic. Rural lots usually need a septic design and a water test. Budget for both up front.
- Season. Frost and mud season affect foundation work. Talk to your builder about timing before you lock in dates.
- Road access. Private or seasonal roads can raise questions at appraisal. Tell me early if that's your lot.
Who I am
Residential home loans in Maine and Florida. DSCR loans on investment and rental properties in 38 states.
Travis Penny, NMLS 1649161 | Vision Mortgage, NMLS 1286953. Subject to credit approval, income, property and program guidelines. Not all applicants qualify. Programs and guidelines can change without notice. Equal Housing Opportunity.
FAQ
- Can I use a VA loan to build on land I already own in Maine?
- Yes. The value of land you've owned for more than a year can count toward the deal, and land you bought within a year counts at cost. Any existing lien on the lot gets paid off at closing.
- Do I need a down payment on a VA construction loan?
- VA loans allow eligible veterans to buy with no down payment. With full entitlement there is no VA loan limit, and with partial entitlement a down payment may be needed above the limit. Not everyone will qualify, and some lenders set their own requirements on construction loans.
- Can I build a camp or second home with a VA construction loan?
- No. VA loans are for a home you'll live in as your primary residence.
- Does my builder need a VA builder ID?
- Not anymore. VA dropped that requirement in March 2025. Your builder still has to meet Maine and local licensing, bonding and insurance rules, and the lender has to approve them.
- Who approves the draws during the build?
- You do. The builder is paid in stages, and you sign off in writing before each draw goes out.
- What if my lot has a well, septic or a private road?
- That's common in Maine and it can work. Budget for the septic design and water test up front, and tell me early about private or seasonal road access so we can plan for the appraisal.
Talk with Travis about your options
Call or text me at (207) 615-7770 or email Travis@travis.mortgage. You can also start on my contact travis page.