
DSCR loans in Wisconsin
Wisconsin DSCR Loans: Your Name or an LLC, the Tax Bill, and City Rental Rules
DSCR loans are for investment and rental properties only. Primary and second homes are available in Maine and Florida. I am not licensed for a primary or second home in Wisconsin.
Travis Penny, Mortgage Broker, NMLS #1649161, Vision Mortgage, LLC NMLS #1286953. NMLS Consumer Access
Last reviewed October 8, 2026
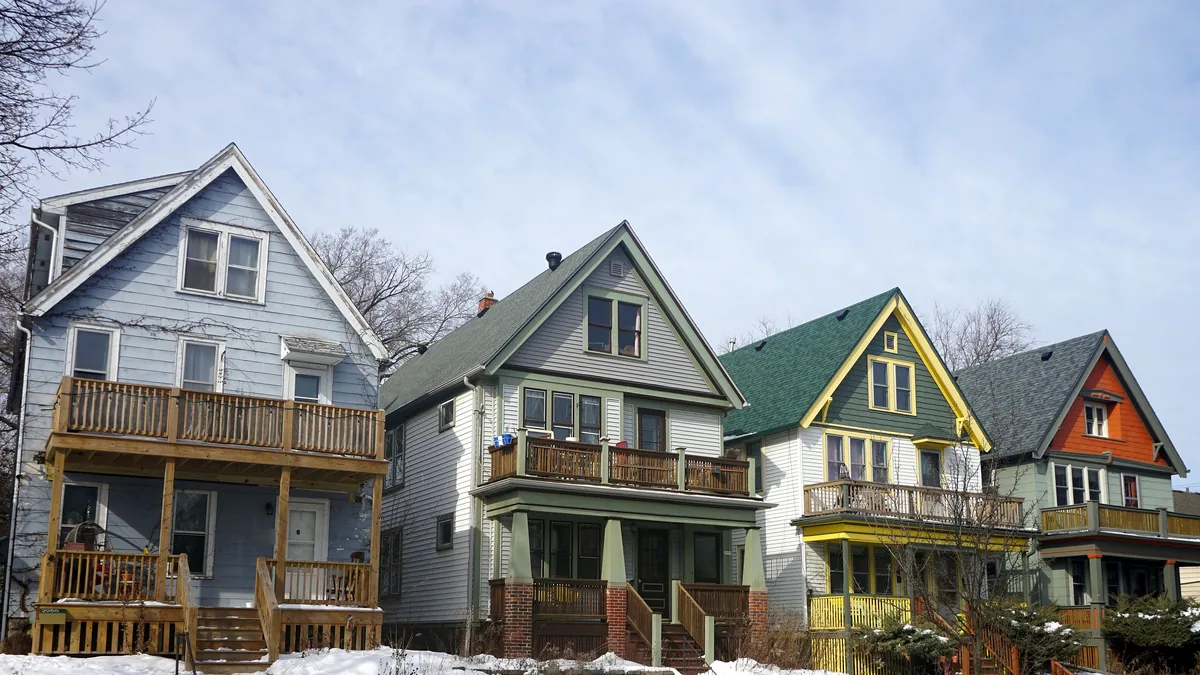
Photo: Michael Barera, CC BY-SA 4.0, via Wikimedia Commons. Cropped, a house number blurred.

I'm Travis Penny, and I started in 2004 and I'm still here. Before you make an offer on a Wisconsin rental, run the rent and the full payment through my DSCR calculator. Then text me at (207) 615-7770 or send the address through my contact page, and I'll tell you which programs fit.
For everything lenders check on a DSCR file, see my DSCR loan requirements guide. The program itself is on my DSCR loans overview, and if you plan to buy in a company, read how DSCR loans work in an LLC.
Yes. Wisconsin is on my DSCR list of 37 states for rentals and investment property. Under LLC vesting required, my licensing table says **No** for Wisconsin, which means title can go in your own name or in an LLC. What shapes a Wisconsin file is the rent, the full payment, a property tax bill that can change once a landlord owns the place, and city by city rules on short-term rentals.
DSCR means debt service coverage ratio. On a Wisconsin rental I divide the supported rent by the whole monthly payment: principal, interest, property taxes, insurance, and association dues if there are any. If the rent covers it, the property carries itself on paper, and your personal tax returns are not the basis of approval. Try your numbers on my DSCR calculator before you write an offer.
The general program is on my DSCR investor loan page. Below is the Wisconsin part: title, the tax bill, the rental markets investors ask me about, and the landlord rules that touch your lease file.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
12.4 business day average to clear to close
My average from loan submission to clear to close is 12.4 business days. That's an average, not a promise. Your timeline depends on your file, the appraisal and title, but when you need speed, I can move fast.
Average of my loans submitted to UWM, from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
Text me at (207) 615-7770
Investment property loans in Wisconsin: what a DSCR file needs
A DSCR loan is one kind of investment property loan, and in Wisconsin it is usually the one that fits investors who don't want their personal income underwritten. Here is what the file has to show.
- A rental, not a residence. A home with 1 to 9 residential units held as an investment, which neither you nor a family member will occupy. Mobile homes and manufactured housing are excluded.
- Supported rent. A lease in place, or market rent from the appraiser. On a Milwaukee upper and lower duplex, each unit's rent is reviewed on its own.
- A complete payment. Taxes based on what a landlord will pay, not the seller's credits, and a landlord insurance quote for the address.
- Credit and reserves. Reviewed program by program, along with cash to close.
- Appraisal and title. An appraisal that includes a rent schedule, and title that clears.
- Vesting. Your own name or an LLC, matched exactly between the deed and the loan.
Each program draws its own lines on these items. I run your property past several of them and then tell you which fit. This is general education, and it is not a loan offer or a promise to lend.
Can you close a Wisconsin DSCR loan in your own name?
Yes. My Licensing page lists Wisconsin with No in the LLC vesting column. A personal name closing works and so does an LLC, and I confirm the specific program's vesting rules on your file before we commit to a path.
If you want an entity, a Wisconsin LLC is formed through the Wisconsin Department of Financial Institutions, and it needs to exist before closing so the deed and the note carry the same name. Shifting a rental you already own into an LLC takes a fresh deed at the county register of deeds, and Wisconsin generally wants an electronic real estate transfer return filed with it. Some transfers are exempt from the transfer fee and some are not, so ask your title company or a Wisconsin attorney before you deed over a property with tenants in it.
Why the seller's Wisconsin tax bill can mislead you
Wisconsin has a property tax credit that only owner occupants get. The Wisconsin lottery and gaming credit applies to a dwelling the owner uses as a primary residence on January 1. The Department of Revenue says plainly that rental units and business property don't qualify. If the seller lived in the home and claimed the credit, the bill you see in the listing reflects a reduction you won't have as a landlord.
Property in Wisconsin is assessed by the local city, village, or town assessor, and the bill is paid to the municipal or county treasurer. When I build the payment on a Wisconsin rental, I start from the parcel's tax record and take out owner-only credits, so the coverage ratio reflects what you will actually pay. If you are unsure of the right figure, the local treasurer or assessor can tell you how the bill is put together.
Milwaukee, Madison, and Green Bay rentals
Milwaukee. A lot of Milwaukee's rental stock is the two-family upper and lower duplex, including the older stacked homes often called Polish flats, with a unit on each level and separate entrances. Those are a natural DSCR fit, and I review the rent on each unit separately. Milwaukee also has small apartment buildings that land in the 5 to 9 unit range, which DSCR covers with a full rent roll review.
Madison. Madison is the state capital and home to UW-Madison, so investors ask me about student and professional rentals there. Count on long-term rent. The City of Madison treats short-term rentals as tourist rooming houses and requires the rental to be the operator's primary residence, along with city and health department permits. An investor-owned Madison property is a long-term lease story.
Green Bay. Green Bay is a smaller market, and game weekends draw interest in short-term stays. Before you count on that income, check the city's licensing and zoning for the address. If short-term use is limited, I qualify the property on long-term rent.
Investors also ask me about the Fox Valley, Kenosha and Racine, La Crosse, and Eau Claire. Whatever the city, I look at the address, the rent, and the full payment for that property, not a statewide average.
How Wisconsin limits local short-term rental rules
Wisconsin sets a statewide floor for rentals. Under Wis. Stat. 66.1014, a city, village, or town cannot ban renting a residential dwelling for 7 consecutive days or longer. For rentals of more than 6 but fewer than 30 consecutive days, a municipality can cap the total at no fewer than 180 days in any 365 day period, and it can require a local license. Anyone operating a short-term rental more than 10 nights a year also needs a state tourist rooming house license.
That floor does not override a residency rule like Madison's, a homeowners association ban, or your lease terms, so the address still decides it. When short-term income is allowed, programs document it differently than a long-term lease. When it isn't, the file runs on long-term rent.
Wisconsin landlord rules that touch your rent file
Most Wisconsin residential rentals fall under the state's Residential Rental Practices rules in Wis. Admin. Code ATCP 134, along with chapter 704 of the statutes. Those rules cover what a landlord has to disclose before taking a security deposit, the tenant's check-in inspection, and the deadlines and itemization for returning a deposit. A lender reads your leases during underwriting, so leases that follow those rules make the rent easier to document.
What I need to review a Wisconsin rental
Send what you already have:
- The address, the municipality, and the unit count
- Leases in place, or your planned rent unit by unit
- The parcel's tax record, with any owner-only credits noted
- An insurance quote written for a rental
- How you'll take title: your own name, or a Wisconsin LLC already filed with DFI
- A clear yes that no one in your family will live there
From there I score coverage with actual numbers and narrow down the programs worth pursuing.
Where Wisconsin fits on my licensing page
Residential home loans in Maine and Florida. DSCR loans on investment and rental properties in 37 states. Wisconsin appears there with No in the LLC vesting column, and the list only covers business purpose lending on 1 to 9 unit residential property the owner won't occupy.
DSCR loans are for investment and rental properties only. Primary and second homes are available in Maine and Florida. A lake place you plan to use yourself, or a Madison condo you will live in, is not a Wisconsin DSCR file I can arrange.
FAQ
Do I need an LLC for a DSCR loan in Wisconsin?
No. Wisconsin is listed with No for LLC vesting on my licensing page. You can borrow in your own name, or set up an LLC through the Wisconsin Department of Financial Institutions ahead of closing and keep its name identical on the deed and the note. Either way, the property has to be a rental or investment you won't occupy.
What do I need for an investment property loan in Wisconsin?
Think of a Wisconsin DSCR file as five things: a 1 to 9 unit residential rental you won't occupy, a lease or appraiser market rent to support the income, rent that clears the whole payment once taxes and insurance are in, credit and reserves the program accepts, and a decision on title, your name or an LLC. Several programs get compared against your property before I recommend one.
Does the Wisconsin lottery and gaming credit apply to my rental?
No. The Wisconsin Department of Revenue limits the lottery and gaming credit to a primary residence owned and occupied on January 1, and it says rental units and business property don't qualify. If the seller claimed it, plan on a higher tax line once you own the property as a rental.
Can I count short-term rental income on a Wisconsin DSCR loan?
Sometimes. State law limits how far a municipality can restrict rentals of 7 days or longer, but cities can still license short-term rentals, and Madison requires the rental to be the operator's primary residence. If short-term use is allowed at the address, programs document that income their own way. If it isn't, I qualify the property on long-term rent.
Can I buy a Wisconsin rental if I live in another state?
Yes. Your home state doesn't matter to a DSCR program. The Wisconsin property's rent does. Put the rent into my DSCR calculator, then text me at (207) 615-7770 with the town and the monthly rent.
Is a Wisconsin DSCR loan for a primary home or second home?
No. In Wisconsin I only arrange DSCR loans as business purpose financing for rental and investment properties. Primary and second homes are available in Maine and Florida. A Wisconsin place you will live in, even for part of the year, falls outside DSCR.
Sources
- Wisconsin Department of Revenue, Lottery and Gaming Credit (sec. 79.10, Wis. Stats.)
- Wis. Stat. 66.1014 (limits on local residential rental restrictions)
- City of Madison Building Inspection, Short-Term Rental Regulations
- Wis. Admin. Code ATCP 134 (Residential Rental Practices)
- travis.mortgage/licensing (DSCR state list and LLC vesting table)
Have a Milwaukee duplex or another Wisconsin rental in mind? Put the rent into my DSCR calculator, then text me at (207) 615-7770 or send the address through my contact page. I'll come back with how the coverage looks and the programs that fit.
Keep exploring
Other states I cover
I do DSCR loans on investment and rental properties in 37 states. See the full list on the DSCR loans overview.
- DSCR loans in Alabama
- DSCR loans in Arkansas
- DSCR loans in Colorado
- DSCR loans in Connecticut
- DSCR loans in Florida
- DSCR loans in Georgia
- DSCR loans in Illinois
- DSCR loans in Indiana
- DSCR loans in Louisiana
- DSCR loans in Maine
- DSCR loans in Michigan
- DSCR loans in North Carolina
- DSCR loans in Ohio
- DSCR loans in Pennsylvania
- DSCR loans in South Carolina
- DSCR loans in Tennessee
- DSCR loans in Texas
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.