

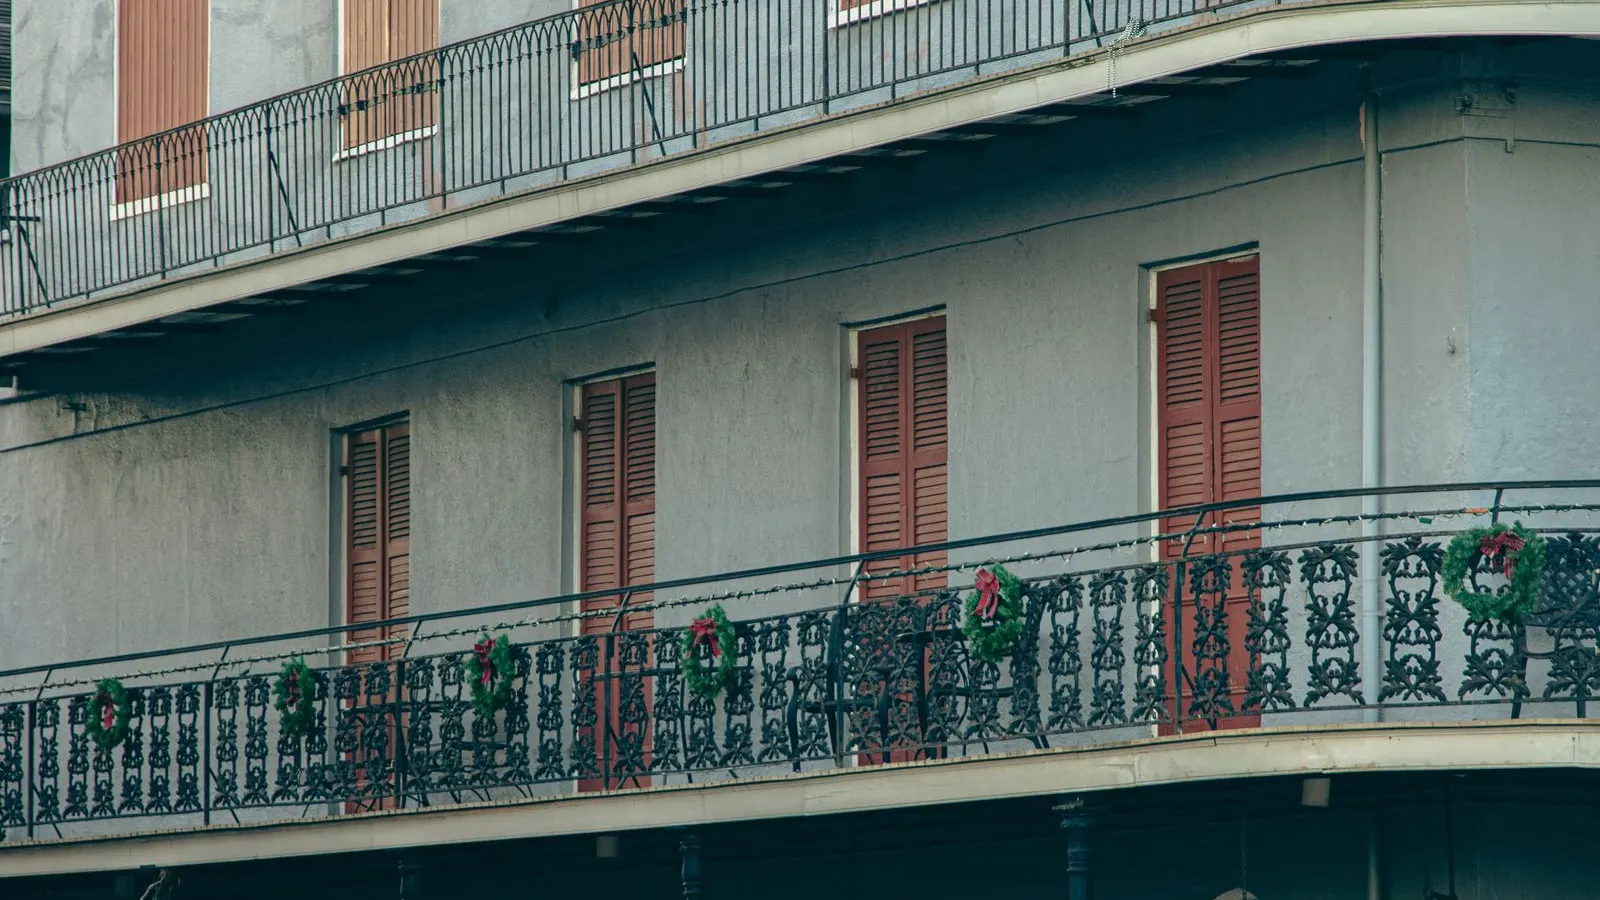
DSCR loans in Louisiana: New Orleans, Baton Rouge, Lafayette, Shreveport and Lake Charles rentals
How I qualify Louisiana rental property on its rent, with parish taxes, the homestead exemption rentals lose, New Orleans short term rental limits and flood and wind insurance.
Travis Penny, Senior Mortgage Broker, NMLS #1649161, Vision Mortgage, LLC NMLS #1286953. NMLS Consumer Access
Last reviewed November 19, 2026
Recent scenario: an investor file I worked through from first call to closing. Read the Maine Non-QM case study.
Illustrative example, not a guarantee. Every file is different.
11.2 business day average to clear to close
My average from loan submission to clear to close is 11.2 business days. That's an average, not a promise. Your timeline depends on your file, the appraisal and title, but when you need speed, I can move fast.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
Text me at (207) 615-7770
Louisiana runs on parishes, and on insurance
A DSCR loan qualifies an investment property on its rent instead of your tax returns. I compare the monthly rent to the full payment: principal, interest, taxes, insurance and any association dues. In Louisiana, insurance is often the line that decides the deal, and taxes are set by parish, not county. I start with a flood zone check and a real insurance quote before anything else.
If you would rather keep personal income off the application entirely, read about the no income DSCR loan, which is for investment property only.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a Senior Mortgage Broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
Buying a rental in Louisiana? I'll tell you quickly if the rent covers the loan. DSCR is for investment properties only.
Why not a lead-site form?
When you reach out here, you talk directly to one Senior Mortgage Broker, Travis Penny. Your information is not sold to a list of lenders, so your phone does not start ringing with strangers. I review your file myself and tell you plainly what fits.
New Orleans: residential short term rentals are limited
New Orleans allows only one non commercial short term rental per block, with room for up to two more by special exception, and the city fills open spots by lottery. The owner has to be a natural person, not an LLC, and the operator has to live on site. Someone buying a rental to run nightly with no one living there won't fit that permit. So in Orleans Parish I underwrite on long term rent.
Long term rentals in New Orleans have their own steps too. Owners of four or more rentals have to register each one with the city's Healthy Homes program.
Baton Rouge and Lafayette
Baton Rouge has demand from state government, LSU and the petrochemical plants along the river. Lafayette is the center of Acadiana, with demand tied to health care, the university and energy work. Both sit in areas where flood zones can change from one street to the next, so I pull the flood map for the exact parcel.
Shreveport and Lake Charles
Shreveport, in Caddo Parish, has lower purchase prices and steady demand from Barksdale Air Force Base across the river in Bossier City. Lake Charles in Calcasieu Parish was hit hard by Hurricanes Laura and Delta in 2020, and insurance there can move a lot from one quote to the next. I want a bound quote, not an estimate.
Louisiana rules that touch the numbers
Homestead exemption. Louisiana exempts the first $75,000 of market value on a home the owner lives in. A rental doesn't get it. If the seller lived there, their tax bill is too low for you, so I recalculate it.
Security deposits. Louisiana sets no statewide cap on the amount. The landlord has one month after the lease ends to return it or send an itemized statement. Willful failure can cost the greater of $300 or double the amount withheld.
Flood and wind. Flood insurance is required in special flood hazard areas, and wind coverage near the coast can come from the state's insurer of last resort when private coverage is hard to find. Both go into the payment.
What I need from you
A lease or the appraiser's rent estimate, a tax estimate without the homestead exemption, a flood determination, an insurance quote and any HOA dues. I finance 1 to 9 unit properties, including condos, but never mobile or manufactured homes. You can close in an LLC or in your personal name in Louisiana. Lenders still review credit, down payment and reserves, and requirements vary by lender.
Illustrative scenario
This is an illustrative example, not a real client. An investor wants a shotgun double in New Orleans' Bywater and asks about renting one side nightly. Neither side will be the investor's home, so the city's non commercial permit isn't an option. I run the ratio on long term rent for both sides, recalculate taxes without the homestead exemption, and get flood and wind quotes for that address. The investor sees whether the deal holds up as a long term rental before making an offer.
Louisiana DSCR FAQs
Can I Airbnb a New Orleans rental I buy with a DSCR loan?
Usually not, because New Orleans limits residential short term rentals to one per block, requires a natural person owner and requires an operator who lives on site. I underwrite New Orleans investment properties on long term rent.
Does the Louisiana homestead exemption apply to a rental?
No, the $75,000 homestead exemption only applies to a home the owner lives in. I take it out of the tax estimate before I check the rent against the payment.
How does flood insurance affect a Baton Rouge DSCR loan?
Flood insurance is part of the payment the rent has to cover, and it's required in special flood hazard areas. I check the flood map for the exact parcel early, since zones can change street by street.
Is a Lake Charles rental a good fit for a DSCR loan?
It can be, as long as the insurance numbers work. Premiums there can vary widely after the 2020 hurricanes, so I get a bound quote before we count on the ratio.
How fast must a Louisiana landlord return a security deposit?
Louisiana gives the landlord one month after the lease ends to return the deposit or send an itemized statement. There's no statewide cap on the deposit amount.
Can I close a Louisiana DSCR loan in my LLC?
Yes, in Louisiana you can close in an LLC or in your personal name. Keep in mind that New Orleans won't issue a residential short term permit to an LLC owner.
More Louisiana landlord and ownership questions
Why are Louisiana closings different from other states?
Louisiana follows a civil law tradition, and a property sale is typically done through an act of sale passed before a notary. The terms and paperwork can look unfamiliar if you have bought elsewhere. Your title attorney or notary walks you through it.
Which court handles a Louisiana eviction?
Depending on the parish and city, Louisiana evictions go to a justice of the peace court, a city court or a parish court. The landlord gives written notice to vacate before filing. Ask a local attorney about timing in your parish.
Does Louisiana's insurance market affect a rental purchase?
Yes. After several major hurricanes, Louisiana homeowners insurance has become harder to place in some areas, and some properties end up with the state backed insurer of last resort. I get a binding quote early, since the premium can make or break the ratio.
Where do I form a Louisiana LLC?
Louisiana LLCs are filed with the Louisiana Secretary of State. I review the articles and operating agreement and confirm who can sign for the company at closing.
Keep exploring
Nearby DSCR states
Other states I cover
I arrange DSCR loans on investment and rental properties in 38 states.
- Alabama DSCR loans
- Alaska DSCR loans
- Arkansas DSCR loans
- Colorado DSCR loans
- Connecticut DSCR loans
- Delaware DSCR loans
- Florida DSCR loans
- Georgia DSCR loans
- Hawaii DSCR loans
- Illinois DSCR loans
- Indiana DSCR loans
- Iowa DSCR loans
- Kansas DSCR loans
- Kentucky DSCR loans
- Maine DSCR loans
- Maryland DSCR loans
- Massachusetts DSCR loans
- Michigan DSCR loans
- Mississippi DSCR loans
- Missouri DSCR loans
- Montana DSCR loans
- Nebraska DSCR loans
- New Hampshire DSCR loans
- New Mexico DSCR loans
- North Carolina DSCR loans
- Ohio DSCR loans
- Oklahoma DSCR loans
- Pennsylvania DSCR loans
- South Carolina DSCR loans
- Tennessee DSCR loans
- Texas DSCR loans
- Virginia DSCR loans
- Washington DSCR loans
- West Virginia DSCR loans
- Wisconsin DSCR loans
- Wyoming DSCR loans
Related DSCR programs
- No ratio DSCR loans
I review rental files that do not fit the usual coverage test.
- DSCR loans for 5 to 9 units
I review unit count, leases and expenses for small rental buildings.
- Short term rental loans
I check permitted rental use and accepted income documentation.
- Fix and flip loans
I review the purchase, renovation plan and proposed sale.
- Fix and hold loans
I review renovation financing and the plan to keep the rental.
- BRRRR loans
I line up the rehab bridge and the DSCR refinance so they fit together.
- Blanket loans
I review multiple rental properties under one financing plan.
- Foreign national DSCR loans
I review investment property financing for foreign national buyers.
- First time investor DSCR loans
I review the rental and reserves when you are buying your first investment.
- DSCR loans in an LLC
I explain title, entity documents and the ownership review.
- Investment property DSCR HELOC
I review rental equity under the separate HELOC eligibility and ownership rules.
Start with my DSCR investor loan overview, review the rent in my DSCR loan calculator, and confirm coverage on my licensing page.
Buying a rental in Louisiana? I'll tell you quickly if the rent covers the loan. DSCR is for investment properties only.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.