

Marcus Lefebvre
Five star rating, no written review.
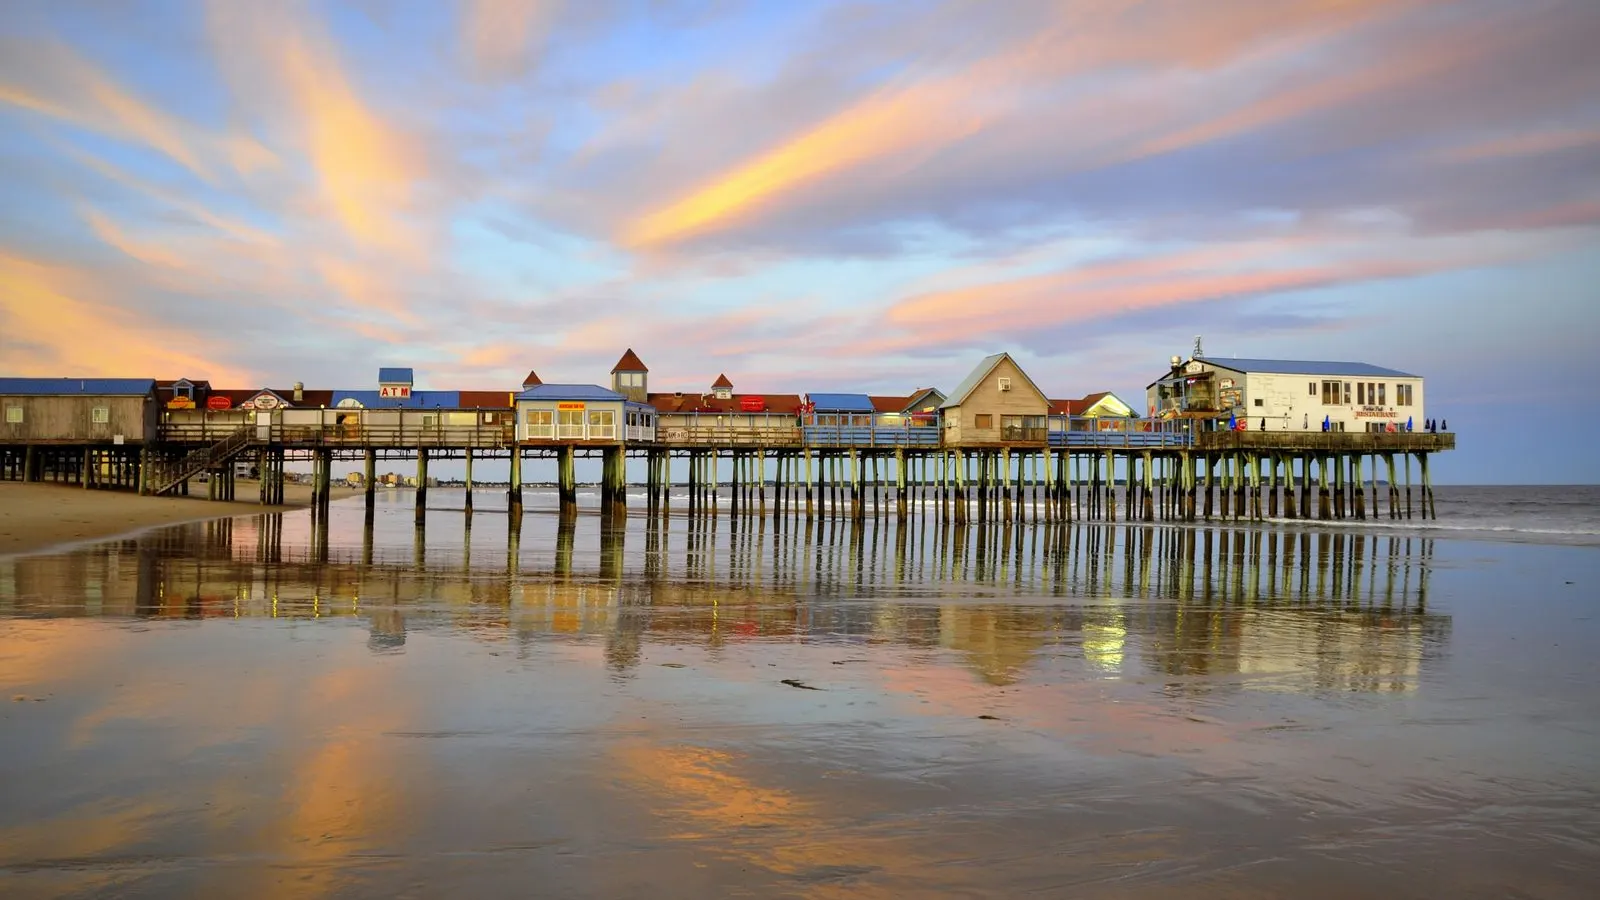
I am a Senior Mortgage Broker at Vision Mortgage, NMLS 1649161, company NMLS 1286953. I review the particular Saco Island, Camp Ellis or inland property before comparing financing rather than carrying assumptions across the river from Biddeford.
Written by Travis Penny, Senior Mortgage Broker, NMLS #1649161
Last reviewed November 14, 2026
I am a Senior Mortgage Broker at Vision Mortgage, NMLS 1649161, company NMLS 1286953. I review the particular Saco Island, Camp Ellis or inland property before comparing financing rather than carrying assumptions across the river from Biddeford.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a Senior Mortgage Broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
Saco Island sits in the river between Saco and Biddeford. A property there deserves a parcel level look at jurisdiction and flood mapping. Converted spaces can have different deeds, associations and occupancy rules. Request the legal description and any building documents before assuming a listing can be financed like a detached home.
An older converted structure may also call for careful inspection of common areas and building systems. Ask who insures and maintains those parts. If an association governs the property, obtain its budget and current insurance information. Do not borrow the project documents from a different mill property across the river. The fact that both buildings began as mills does not make them one financing file.
Source: City of Saco.
Read more: Maine home loans.
If this is your first home, start with my first time home buyer Maine guide. To see a payment with taxes and insurance, use the Maine mortgage calculator, and read about the mortgage costs beyond the loan before you set a budget.
If you are searching for a Senior Mortgage Broker near me in Greater Portland, my Portland page explains how I work with buyers from my office on Warren Avenue.
Just across the river, I also cover home loans in Biddeford.
Camp Ellis and Ferry Beach are coastal parts of Saco, but an offer on either still needs a check of the exact parcel. Ask about flood mapping, available insurance and any past repairs. A seasonal cottage may have different heating, water or foundation details from a year round residence nearby. Inspect the home's present condition rather than treating a beach address as proof of how it can be occupied.
Ask whether coastal access is public, deeded or simply nearby. Confirm the legal lot and applicable municipal rules before planning a renovation. If the home is part of an association, its obligations and insurance need review too. A seller's description of seasonal use is not a substitute for documents and a current inspection.
Read my guide to a second home loan in Maine.
Comparing Camp Ellis with beaches farther south? My southern Maine coast home loans page covers York, Ogunquit, Kennebunkport and Old Orchard Beach. Right next door, my Old Orchard Beach Maine real estate page covers OOB homes and condos.
Source: Saco municipality.
Saco properties farther west can raise access, well or septic questions instead of the coastal concerns that dominate a Camp Ellis search. Ask for system records, tests and maintenance history where a property uses private services. On a private road, request the recorded access and maintenance agreement. The mailing city alone does not tell you which infrastructure serves a home.
Some buyers consider USDA financing for rural edges, but eligibility must be checked on the official map for the precise address and household. An eligible USDA buyer does not need a down payment under the program, subject to its other rules. Do not infer eligibility from the appearance of surrounding fields or from another property's approval.
Source: USDA address eligibility.
Read more: Maine USDA guide.
A river location near downtown differs from a beach cottage, and both differ from a west Saco house. Check the flood designation for the actual address, ask whether past work has permits and seek an insurance review. If an apparent dwelling unit is part of a riverfront property, confirm its permitted status before counting any rent.
If you will buy before selling another home, explain the timing and obligations early. A bridge loan is one option to review, not a guarantee that the new house will qualify. The offer should reflect the property records, inspection and financing timeline. I can compare a purchase path after you have those facts in hand.
Source: Saco official site.
Read more: Maine bridge loans.
An eligible primary residence can be assessed for FHA, VA or a conventional program depending on the buyer and property's condition. A condo or converted mill unit adds project documents. A coastal second home adds occupancy and insurance questions. A rural address adds site and access documents. Starting with the property's legal type prevents a financing discussion from becoming a generic menu.
Request current city assessment information, any association packet, inspection results and the insurance quote applicable to that home. For a property being converted from seasonal use, ask local officials what is permitted before relying on future renovations. I will discuss financing based on its documented condition and your intended use, not an assumed future state.
Read more: Maine FHA financing, Maine VA financing.
Verify the parcel jurisdiction, deed, building association documents and flood designation. A nearby mill conversion may have different rules.
Review its legal use, heating, water, condition and insurance for the actual parcel. The listing's seasonal description is not enough.
Use the USDA property eligibility search for the exact address, then separately review household and property requirements.
Five star rating, no written review.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.