

Kennebunk Maine real estate: financing a home downtown, near the beach or inland
Travis Penny, Senior Mortgage Broker, NMLS 1649161
Reviewed by Travis Penny, NMLS 1649161
Last reviewed November 19, 2026
Quick answer: I arrange mortgages for people buying Kennebunk Maine real estate: a Federal style house on Summer Street, a shingled place a short walk from Gooch's Beach, a newer cape in West Kennebunk, a condo near the Lower Village, or a wooded lot in Arundel. I do not list or sell homes. Your agent helps you find the house and I build the loan around it. In Kennebunk the neighborhood tends to decide the questions: flood maps and price near the water, condition and insurance on the old homes in town, and the well and septic once you head inland. Approval depends on your credit, income, assets, the property and program rules. Not everyone will qualify.
Travis Penny, NMLS 1649161 | Vision Mortgage, NMLS 1286953. Subject to credit approval, income, property and program guidelines. Not all applicants qualify. Programs and guidelines can change without notice. Equal Housing Opportunity.
Who buys in Kennebunk
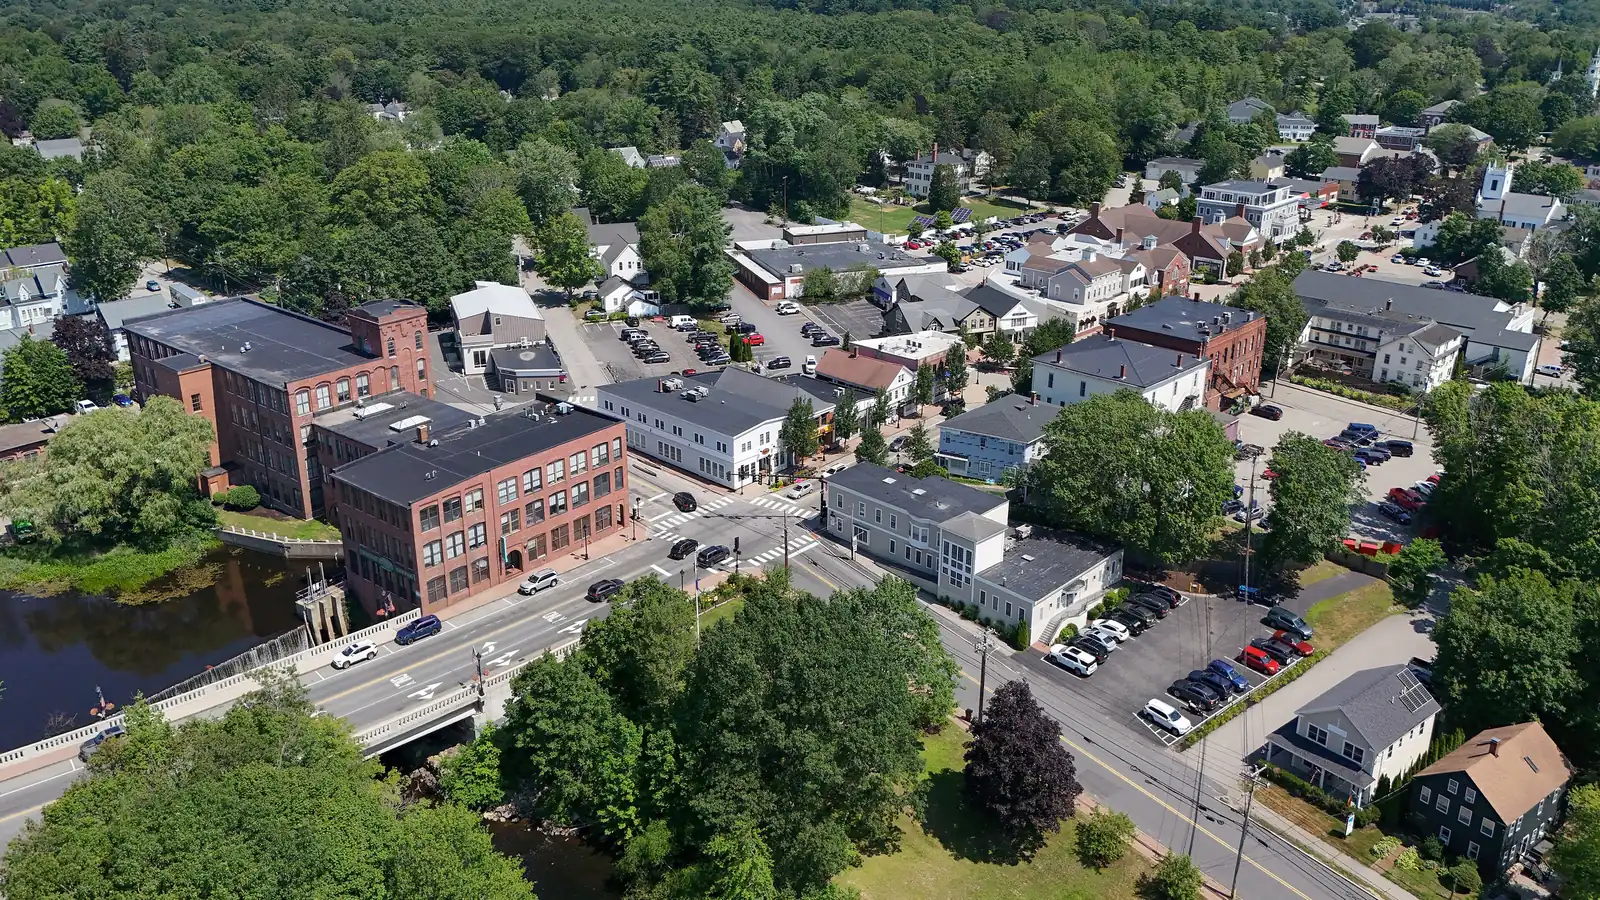
Kennebunk is a town of roughly 11,000 people in York County, with the Mousam River running through its downtown and the Kennebunk River forming its line with Kennebunkport. It is a real year round town. The Maine Turnpike has an exit here, Portland is roughly half an hour north, and the Downeaster train stops next door in Wells. So I see a wide mix of buyers: families moving for the schools, people who commute to Portland or the Seacoast, nurses and teachers, remote workers, retirees, and folks from Massachusetts who want a summer place they can grow into.
My name is Travis Penny. I work as a Senior Mortgage Broker, NMLS 1649161, with Vision Mortgage NMLS 1286953, and I hold licenses in Maine and Florida. Being a broker lets me shop one application among a handful of wholesale lenders and pick the one whose rules match the property, and you talk to me, not a call center, until you get the keys. I started in 2004 and I'm still here.
Four parts of town, four sets of questions
Downtown and the Summer Street area. Main Street runs past the brick mill buildings on the river, and the streets around it hold some of the best preserved old homes on the coast, including the captains' houses along Summer Street. These homes are usually on town water and sewer, and they tend to finance normally. What I watch is the condition list: old wiring, aging roofs, chimneys, and any flaking paint on a house built before 1978 if you are using FHA or VA.
The Lower Village. Along Route 9 near the bridge to Dock Square you find older homes, a few small condo projects, and buildings that mix shops with apartments. A mixed use building or a house with an apartment over the garage is a different file than a plain single family home, so tell me how the space is set up before you write the offer.
Kennebunk Beach. Beach Avenue and the streets behind Gooch's, Middle and Mother's beaches hold shingled cottages, large shore homes and some newer builds. Prices here often run past the conforming limit, which means a jumbo loan. Not everyone will qualify. Many of these lots also sit in a mapped flood zone, and I cover that below.
West Kennebunk and the inland side. West of the turnpike and out toward the Kennebunk Plains, you see capes, colonials and ranches on bigger lots, newer subdivisions, and open land. Expect a private well and septic on many of these. That is routine in Maine, but plan on a water test and a septic inspection and order them early.
Making Kennebunk your main address
Living here full time opens up the most options. For most buyers I line up conventional financing next to an FHA loan in Maine, and veterans can add a Maine VA loan to that comparison. USDA depends on location, and the coastal side of town generally falls outside it, though a few inland addresses nearby might fit; I run the exact address instead of guessing. Buying your very first place? My Maine first time home buyer guide puts the steps in order. To see a monthly figure with taxes and insurance built in, try my Maine mortgage calculator.
Own a business or work on commission? Your returns tell the income story on a primary home, and my self employed home loans in Maine page shows what underwriters pull from them.
Beach homes, flood maps and insurance
Close to the sand, the tidal marsh and the river mouths, the flood map can shape the whole deal. A house inside a FEMA special flood hazard area must carry flood coverage before the lender will close, and that premium is added to your monthly housing cost when we qualify you. Ask your agent whether an elevation certificate exists, and price the coverage on that exact address while your contingencies are still open.
Homeowners insurance can be its own hurdle on an older shore house, so I like to see a quote before the appraisal is ordered. And if you hope to expand or replace a cottage close to the water, check what the town will allow first. That limits your plans more than the loan, but it changes what the house is worth to you.
Summer place or rental property: pick one up front
A lot of my Kennebunk calls come from people in Massachusetts, Connecticut or New Hampshire who want a getaway they can reach in a couple of hours. That works as a second home when it is a single unit that your own family spends time in. A handful of rented weeks while you are back home usually poses no problem; handing the calendar to a rental company does. On conventional financing, a getaway like this may need as little as 10% down. Treat that figure as an educational maximum and not an offer. Not everyone will qualify. For the occupancy rules spelled out, see my vacation home loans page.
When the honest answer is that guests will fill it most weeks from June to October, we finance it as a rental from day one. With DSCR, the lender sizes the loan off what the house can rent for, so your W2 or tax returns play a much smaller role. DSCR is strictly for investment property, and I can place it in 38 states; my Maine DSCR loans page has the details. Labeling a rental as a second home to land better terms is occupancy fraud. I will not write a loan that way. Before you build a budget on summer rent, look up the town's current short term rental rules. Not everyone will qualify.
Condos in Kennebunk
Kennebunk condos run from units carved out of old buildings near downtown and the Lower Village to newer townhouse communities on the inland side. Two approvals happen on a condo: yours and the building's. Underwriting will want the association's annual budget, its savings for future repairs, the master policy, the share of units that are rented, and word of any lawsuit. Request that package the day your offer is signed. Tiny associations, or ones full of seasonal renters, sometimes miss the standard checklist, and my non warrantable condo loans page walks through what happens then.
Land and building in Kennebunk and Arundel
Arundel, which borders Kennebunkport on the north, draws buyers who want acreage, a newer house and quieter roads, and West Kennebunk has open parcels too. If you plan to put up a house, my Maine one time close construction loan guide shows how the lot purchase and the build can share one closing. Conventional versions of that loan cover a full time residence, a getaway or a rental, while townhouse style attached units are excluded, and the VA and FHA versions are limited to a house you will occupy. Prefer to own the dirt first and break ground in a few years? My Maine land loans page covers that path. Not everyone will qualify.
Already own in Kennebunk?
Values in town have climbed, so many owners are sitting on real equity. The plans I hear: heat pumps, a kitchen in an old captain's house, helping a grown child buy, or putting money down on a winter place in Florida. You can tap that equity through a Maine HELOC or a home equity loan and leave your current mortgage alone. Not everyone will qualify.
Kennebunkport, Arundel and Wells
Most Kennebunk buyers look across the town lines too.
- Kennebunkport has Dock Square, Cape Porpoise and Goose Rocks Beach, and prices that often call for jumbo financing. My southern Maine coast home loans page covers Kennebunkport second homes in depth.
- Arundel is more rural, with newer homes, land and a private well and septic on most lots.
- Wells, to the south, has long sandy beaches, plenty of condos, and inland neighborhoods west of Route 1 where year round buyers often find more house for the money.
If you are also weighing Old Orchard Beach or Saco, my Old Orchard Beach Maine real estate and Saco pages are good next stops.
What to send me first
- A link to the listing, plus which neighborhood it sits in
- Whether you will live there, visit, or rent it
- Construction year, how it is heated, and public utilities versus a private well and septic
- Flood zone or elevation notes from the listing, and the condo association name when relevant
- How much you plan to put down, and the account it will come from
Reach me by phone or text at (207) 615-7770, by email at travis@travis.mortgage, or through my contact page. Want a quick way to read a listing sheet before you tour? My homes for sale in Kennebunk Maine guide breaks it into six details.
Frequently asked questions
Do you sell real estate in Kennebunk, Maine?
No. Listing and showing homes is your agent's job. Mine is the mortgage: I am a Senior Mortgage Broker who lines up financing for the house you pick. I started in 2004 and I'm still here.
Will FHA or VA work on a historic house near Summer Street?
In many cases. Expect the appraiser to study the roof, heating, electrical and any loose paint if the home dates before 1978, and certain fixes might be required ahead of closing. Not everyone will qualify.
Do Kennebunk Beach homes need flood insurance?
It depends on the map. Inside a FEMA special flood hazard area the coverage is mandatory for the loan, and plenty of streets by the beaches and river mouths are mapped that way. Price a policy for the specific address before your contingencies run out.
What if the Kennebunk home costs more than the conforming loan limit?
Then it needs a jumbo loan, which usually means more reserves and a closer look at income and the appraisal. I compare jumbo options for primary and second homes in Maine. Not everyone will qualify.
What is the smallest down payment for a Kennebunk getaway?
On a conventional second home loan it may be as little as 10% of the price, which is an educational maximum rather than a quote. Credit history, the house itself and condo rules can all push it higher. Not everyone will qualify.
Is DSCR an option for a Kennebunk summer rental?
Yes, as long as it truly is a rental. DSCR leans on expected rent instead of your paystubs, and it is never used on a house where you or relatives will stay as residents. Not everyone will qualify.
Could I buy a lot in Arundel or West Kennebunk and build on it?
You can. One loan with a single closing can fund the land and the construction. Conventional versions fit owner occupied, getaway or rental plans, and the government backed versions require you to live in the finished house. Not everyone will qualify.
Can I take equity out of my Kennebunk home without refinancing?
Usually, if the numbers support it. A line of credit or a fixed equity loan goes in second position, so the mortgage you already have is untouched. Not everyone will qualify.
Keep exploring
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.