One Time Construction Loan: How It Works, VA vs FHA vs Conventional
I'm Travis Penny, a Senior Mortgage Broker. I started in 2004 and I'm still here. I do residential loans in Maine and Florida, DSCR loans in 38 states, and construction financing is work I genuinely enjoy walking people through.
The two loan way vs the one time way
Building used to mean two loans. You took a short term construction loan to pay the builder, then when the house was done you applied all over again for a permanent mortgage. That meant two approvals, two closings, two sets of closing costs, and the risk that your income, credit or the market changed before the second loan.
A one time construction loan (also called a one time close or single close construction loan) combines both. You're approved for the build and the permanent mortgage at the start. One application. One closing. One set of closing costs.
How it works, start to finish
1. Preapproval. We review your credit, income, assets and debts and set a budget for the whole project: land, construction and closing costs.
2. Builder, plans and contract. A licensed builder is required; owner builders aren't allowed. Your builder, plans and budget need to be set before you make an offer. The builder provides a signed construction contract, plans, specs and a cost breakdown, and must be reviewed and approved for the loan.
3. Land. A land purchase or payoff can often be rolled into the same loan. Equity in land you already own may help toward the down payment, depending on the program.
4. Appraisal. The appraiser values the home as it will be when finished, based on the plans and specs.
5. One closing. You sign once. The construction phase and your permanent mortgage are both set up here.
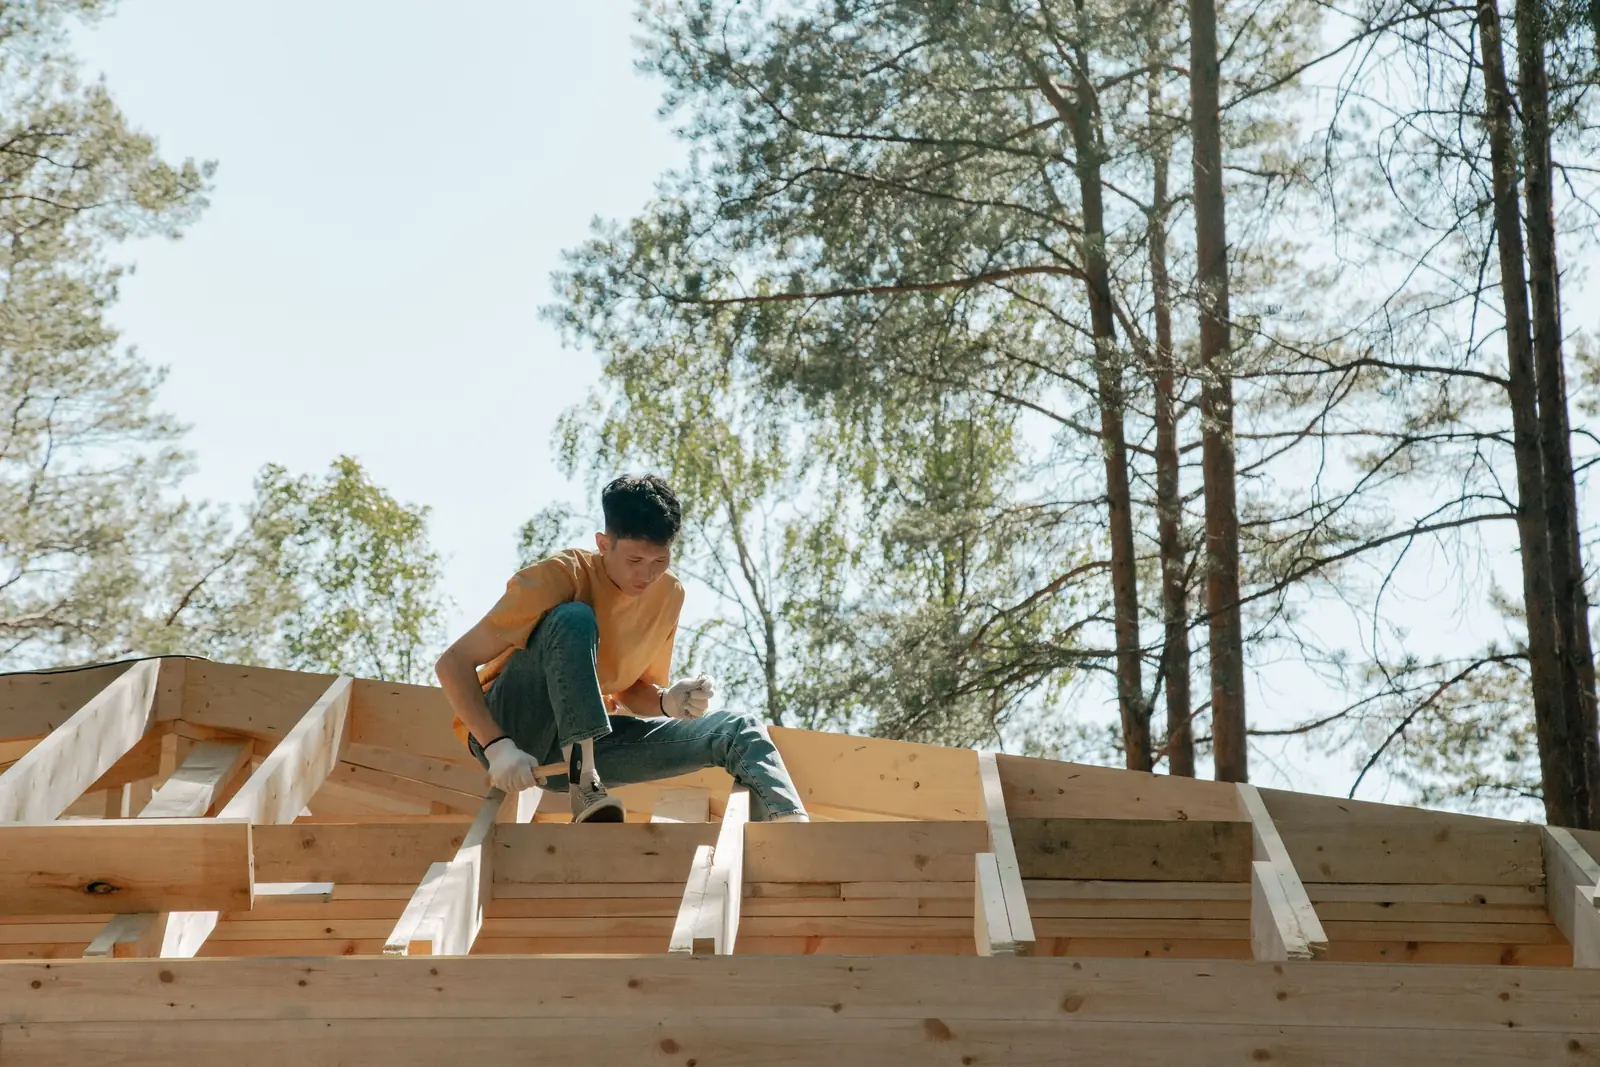
6. The build and draws. Funds are released to the builder in stages, called draws, as work is completed and inspected. Your builder never gets a lump sum up front.
7. Conversion. When the home passes final inspection, the loan rolls into your permanent mortgage and you move in.
Want the FHA version in detail? See how an FHA construction loan works, step by step.
VA vs FHA vs conventional at a glance
VA one time close. For eligible veterans, service members and some surviving spouses. VA allows 0% down for eligible veterans, which is a big deal when you're building. Not everyone will qualify. The home must be your primary residence. Details are on my VA one time close construction loan page.
FHA one time close. Built for buyers with smaller down payments or credit that isn't perfect. FHA allows as little as 3.5% down with a 580+ credit score. Not everyone will qualify. It's for a primary residence, and FHA loan limits by county apply. See the FHA one time close construction loan page.
Conventional one time close. A good fit for buyers with stronger credit and some savings, or anyone whose project is bigger than government loan limits allow. Conventional financing may be available for second homes in some cases. Not everyone will qualify. Down payment depends on the loan and your profile. See the conventional one time close construction loan page.
Building in a rural area? There's also a USDA one time close construction loan. The property must be in a USDA eligible rural area, and you must meet USDA income limits.
Which one is right for you?
A simple way to think about it:
- You served: start with VA.
- Smaller down payment or rebuilding credit: look at FHA.
- Strong credit, larger project, or not a primary residence: look at conventional.
The honest answer comes from your numbers, your builder and your lot. That's what the first conversation is for.
What applies to all of them
- A licensed, approved builder. Licensed, insured, and reviewed for the loan. Owner builders aren't allowed, and your builder, plans and budget need to be set before the offer.
- A buildable lot. Legal access, utilities or a well and septic plan, and zoning for a single family home.
- A real timeline. Closing can happen in as little as 15 to 20 days when builder and project approvals move fast, but plan on about 45 days. The build takes several months to about a year depending on the home, the builder and the weather.
Want to budget the whole thing? Read what a one time close construction loan costs and who qualifies for a one time close construction loan in Maine.
Building in Maine or Florida
Construction lending is local. In Maine, winter schedules, wells, septic design and road access come up a lot. In Florida, it's often permitting, site work and insurance. I know what the paperwork needs to look like before it reaches underwriting. Learn more about one time close construction loans in Maine and one time close construction loans in Florida.
Ready to start?
Get preapproved first so you know your number before you fall for a floor plan.
Start your application · Travis Penny, Senior Mortgage Broker, NMLS 1649161
FAQ
- What is a one time construction loan?
- It's a single loan that pays for building your home and then becomes your permanent mortgage. You apply once and close once, and the loan converts when construction is finished.
- Is a one time close loan better than a two loan construction setup?
- For many buyers, yes. You avoid a second approval and a second set of closing costs, and you aren't exposed to changes in your finances between the build and the permanent loan.
- Can I get a one time construction loan with no money down?
- VA allows 0% down for eligible veterans. Not everyone will qualify. USDA may also be an option if the property is in a USDA eligible rural area and you meet USDA income limits.
- What's the minimum down payment on an FHA one time close loan?
- FHA allows as little as 3.5% down with a 580+ credit score. Not everyone will qualify.
- Can I be my own builder?
- No. These loans require a licensed, approved builder working under a signed construction contract. Owner builders aren't allowed.
- Where do you offer one time construction loans?
- I do residential loans in Maine and Florida, so one time construction loans are available in both states.