
Rangeley Maine real estate: financing a home, camp or land in the Rangeley Lakes
Travis Penny, Senior Mortgage Broker, NMLS 1649161
Reviewed by Travis Penny, NMLS 1649161
Last reviewed November 10, 2026
Quick answer: I arrange loans for primary homes, second homes, lake camps and land to build on in Rangeley, Oquossoc and the plantations around them. I do not list or sell homes. You find the property, and I arrange the loan. Up here the questions that decide a loan are winter questions: can a car reach the house in February, does it hold heat, where does the water come from, and how was the roof built for the snow. I go through those with you before you sign anything. Approval always comes down to your credit, your income, the property itself and the guidelines of the program. Not everyone will qualify.
Travis Penny, NMLS 1649161 | Vision Mortgage, NMLS 1286953. Subject to credit approval, income, property and program guidelines. Not all applicants qualify. Programs and guidelines can change without notice. Equal Housing Opportunity.
Rangeley real estate is mountain lake real estate
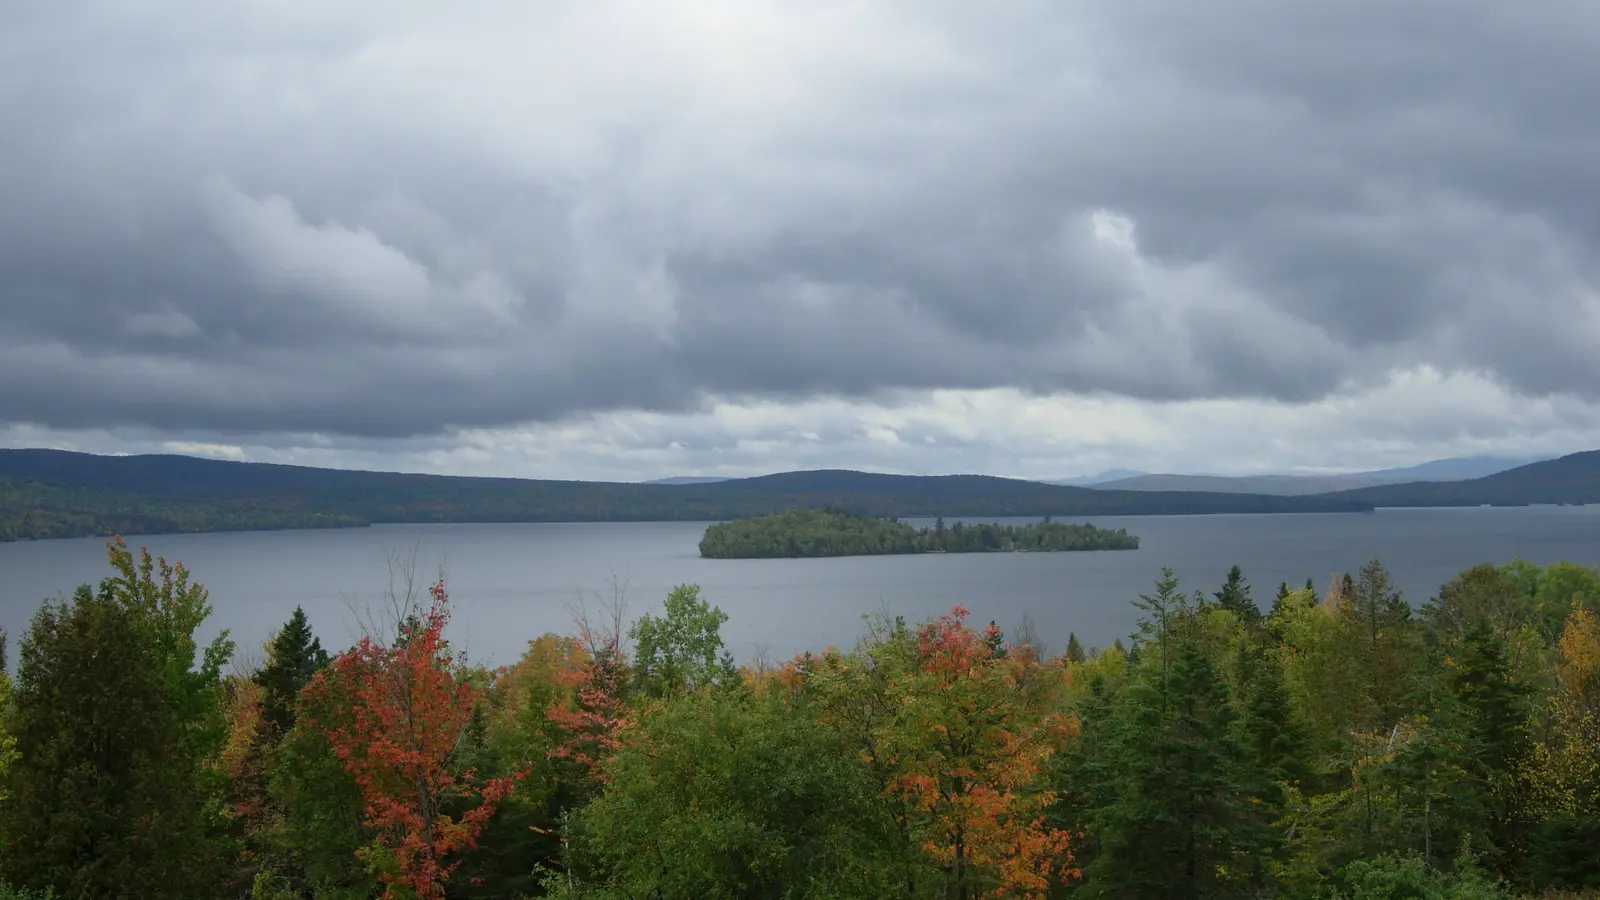
Rangeley sits in Franklin County on the northeastern shore of Rangeley Lake, about 1,500 feet above sea level. The town takes in Rangeley village at City Cove, Oquossoc at the northwest tip of the lake where Routes 4 and 17 meet, and smaller places like Mooselookmeguntic, Bald Mountain, Mountainview and South Rangeley. Rangeley Lake drains through the short Rangeley River into Mooselookmeguntic Lake, which a dam long ago joined to Cupsuptic Lake.
The region grew up as a summer resort, so a big share of the housing started life as camps, cabins and summer cottages. Some have been turned into insulated houses people live in all year. Others still close up after foliage season. When you search Rangeley Maine real estate, both kinds show up next to each other, often at similar asking prices, and they are not the same loan.
Homes for sale in Rangeley Maine: three kinds of buyers
The people who call me about homes for sale in Rangeley Maine usually fall into one of three groups.
- People moving here to live. They work locally, work remotely, or are retiring to the lakes. This is a primary home, and the program menu is the widest.
- Families buying a second place. They live in southern Maine, Massachusetts, Connecticut or farther away and want a lake house for summers and a ski base near Saddleback in winter.
- People who want land. They have found a wooded lot or a lake lot and plan to build, now or later.
Tell me which one you are on the first call. It changes the program, the down payment and what the appraiser will be asked to look at.
I'm Travis Penny, Senior Mortgage Broker, licensed in Maine and Florida. Because I work as a broker instead of for a single bank, I can put your file in front of several lenders, and you still have one person to call from the first conversation until you get the keys. I started in 2004 and I'm still here.
Houses for sale in Rangeley Maine that you will live in
If Rangeley will be home, the options I line up side by side are conventional financing, an FHA loan in Maine, a Maine VA loan for veterans and service members, and a USDA loan when both the property location and the size of your household income qualify. Much of western Maine is rural, so I run USDA eligibility on the actual street address rather than guess from the town name.
Buying for the first time? Start with my Maine first time home buyer guide. Business owners and contractors can see how I handle their paperwork on a primary residence on my self employed home loans in Maine page.
A Rangeley lake house as a second home
A second home loan is built for a single unit that your household really uses, a few weekends or a whole summer, while your main residence stays somewhere else. Picking up rent for a handful of weeks when you are not there is usually acceptable. Once a rental manager or program decides when you are allowed to stay, the lender no longer sees it as a second home.
Lenders generally ignore projected rent when qualifying a second home, so your own paycheck or business income has to carry it. If the honest plan is to rent the place to summer anglers and winter skiers most of the year, we should write it up as an investment property instead. That means a bigger down payment, and under some programs the rent can count toward qualifying. DSCR financing is one of those programs, and I use it only for investment property, in 38 states; details are on my DSCR investor loans page. Look into the town's rules on short stays before you build a budget around rental money. Not everyone will qualify. For more on second home rules in general, see my vacation home loans page.
Lake camps on Rangeley Lake, Mooselookmeguntic and Cupsuptic
On a camp, the appraiser and lender want to see a dwelling someone could live in through a western Maine winter: a permanent heat source, water that runs in January, a working septic system and a road you can reach. A camp that meets that can often be financed like any house. A camp with a drained water line, no insulation and a road nobody plows usually falls outside what a regular mortgage will cover, and I would rather say so before you make an offer.
Shorefront lots also come with shoreland zoning, so if you plan to expand a camp or replace it, find out what the rules allow on that specific lot. For camps in other parts of the state, read my Maine camp and lake house loans guide.
Snow load, roofs and heating
Rangeley gets long winters with deep snow. On an existing house, I would ask the home inspector to look hard at the roof framing and any sagging, the age of the heating system, and whether pipes run through spaces that freeze. Those are the items that tend to come back from an appraisal as repairs. On a new build, ask your builder how the roof is designed for the snow at this elevation before you sign the contract.
Wells, septic and the water question
Outside the village center, expect a drilled well and a private septic system. Lenders accept both when they work. Some camps draw water straight from the lake, and that can be a problem for a year round loan, so tell me early if the listing mentions a lake line or a shared well. A water test and a septic inspection are cheap compared to what they can save you.
Private roads and seasonal roads
A lot of Rangeley area camps sit on private camp roads. If the road is graded, sanded and plowed every winter, lenders rarely object. Underwriting will still ask who is responsible for it and how the owners split the bill, so ask the seller for the road association documents or a written road maintenance agreement right after you go under contract. A road that is open only in the warm months points toward a seasonal camp, and that usually is not a standard mortgage.
Land for sale in Rangeley Maine: buying a lot to build
Plenty of people searching land for sale in Rangeley Maine want to build a house on it. If you are ready to build, a one time close construction loan in Maine rolls the lot purchase, the construction draws and the long term mortgage into a single closing. The conventional version works whether the finished house will be where you live, a getaway or a rental; attached condo units are excluded. The VA, FHA and USDA versions are only for a house you will occupy as your main home. The programs I arrange require an approved builder; you cannot be your own builder. Not everyone will qualify.
If you want Rangeley Maine land for sale now and plan to build years from now, that is a standalone land purchase. Those loans are hard to find and usually come from local banks with larger down payments, and I will tell you that plainly on the first call. My Maine land loans page explains the difference.
Before you commit to a parcel, check the soil and septic design, the well, power, legal road access and the survey. Dallas, Rangeley and Sandy River Plantations next to the town are covered by the state Land Use Planning Commission's zoning plan for the Rangeley Lakes region, so permits there run through the state commission rather than a town planning board. Find out which rules apply to your lot before you buy.
Camps on leased lots
Some Maine camps sit on land the owner leases rather than owns. If a Rangeley area listing says leased lot, send me the lease before you make an offer. A lender looks at how long the lease runs, whether it is recorded and whether it can be transferred and mortgaged. On conventional loans the lease generally must run at least 5 years past the loan's maturity. My leased land home loans page explains what I check. Not everyone will qualify.
Using equity from your main home
Already own a home in Maine or Florida? Borrowing against it is often the simplest way to fund a Rangeley purchase. A Maine HELOC, a Florida HELOC or a home equity loan can supply the down payment, and on a modest camp or lot it can sometimes cover everything. I will compare that against a separate mortgage on the Rangeley property so you can see both. After roughly six months of owning the second home, certain second mortgage programs let total financing reach 85% of what it is worth. Treat that figure as an educational maximum, not a promise. Not everyone will qualify.
Ski homes near Saddleback
Saddleback is just outside town in Sandy River Plantation. A house near the mountain is financed the same way as any Rangeley home: primary, second home or investment. If you are looking at condos at Sugarloaf, Sunday River or Bethel instead, my Maine ski home and condo loans page covers condo project reviews.
Buying from away
Plenty of Rangeley buyers live in other states, and that works fine. As long as the property is in Maine, the whole process can run over the phone, by text and by email, and many closings can be done remotely. My owner occupied and second home financing covers Maine and Florida properties only; investment DSCR covers 38 states.
What to send me
- The listing link or address
- Your plan for it: full time home, part time getaway, or mostly a rental
- Well or town water, septic or sewer, and anything about a lake water line
- Who plows the road, and whether it is open all year
- How the house is heated, and the age of the roof if you know it
- For land: the lot listing, survey if any, and your builder and timeline
- For a leased lot: the full lease
- How much you plan to put down and which account it comes from
- Your last pay stubs and two years of tax returns, or a quick summary of how you get paid if you own a business
That is enough for me to match you to a program and spot appraisal trouble early. Got a property picked out already? Reach out here.
You can reach me by call or text at (207) 615-7770 or by email at travis@travis.mortgage. Want the short version first? My Rangeley Maine home loan article sums it up.
Frequently asked questions
Do you sell or list homes or land in Rangeley?
No. My only job is the mortgage. Work with whichever agent or listing site you prefer, and bring me the property when you are ready to finance it.
Can I buy a year round home in Rangeley with FHA, VA or USDA?
In many cases, yes. Which one fits comes down to your credit, income and the house itself. USDA has location and household income tests, so I look up the specific property. Not everyone will qualify.
Can a Rangeley lake camp be my second home?
Yes, if you keep a main home elsewhere, use the camp yourself part of the year, and the camp has permanent heat, working water and winter road access. A camp that gets closed up for the winter is far tougher to finance. Not everyone will qualify.
Can you finance land for sale in Rangeley Maine?
If you plan to build soon, a one time close construction loan can cover the lot and the house in one closing. If you only want to hold the land, standalone land loans are hard to find and usually come from local banks. I will tell you which applies on the first call.
Can I buy a lot and build a second home in one loan?
A conventional one time close construction loan can be used for a second home with an approved builder. VA, FHA and USDA construction are for a home you will live in. Not everyone will qualify.
Is a private camp road a problem?
Usually not, when it is kept open all winter. Expect underwriting to ask for the road association documents or a signed maintenance agreement, so request them from the seller early. A summer only road is a different conversation.
What if the camp is on a leased lot?
Some homes on leased land can be financed. The lease, title and property all have to meet the program rules, and on conventional loans the lease generally must run at least 5 years past the loan's maturity. Send me the lease first. Not everyone will qualify.
Can I rent my Rangeley place to summer and ski visitors?
Occasional rentals when you are not using it usually do not break a second home loan. If rental income is the real purpose, or a management company sets your stays, it belongs in an investment loan instead. Not everyone will qualify.
Keep exploring
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.