
Maine camps and lake houses
Camps for sale in Maine: how to finance a camp, cabin or lake house
Travis Penny, Mortgage Broker, NMLS 1649161, Vision Mortgage, LLC NMLS 1286953.
Reviewed by Travis Penny, NMLS 1649161
Last reviewed October 19, 2026
Quick answer: Yes, you can finance most camps for sale in Maine, as long as the camp itself checks out. A camp, cabin, cottage or lake house you use yourself part of the year is usually a second home loan, and one you live in full time can be a primary home loan. Before you make an offer I look at four things: how you get there in winter, where the water comes from, the septic, and the shoreland rules. All loans are subject to credit, income, property and program guidelines. Not everyone will qualify.
Travis Penny, NMLS 1649161 | Vision Mortgage, NMLS 1286953. Subject to credit approval, income, property and program guidelines. Not all applicants qualify. Programs and guidelines can change without notice. Equal Housing Opportunity.
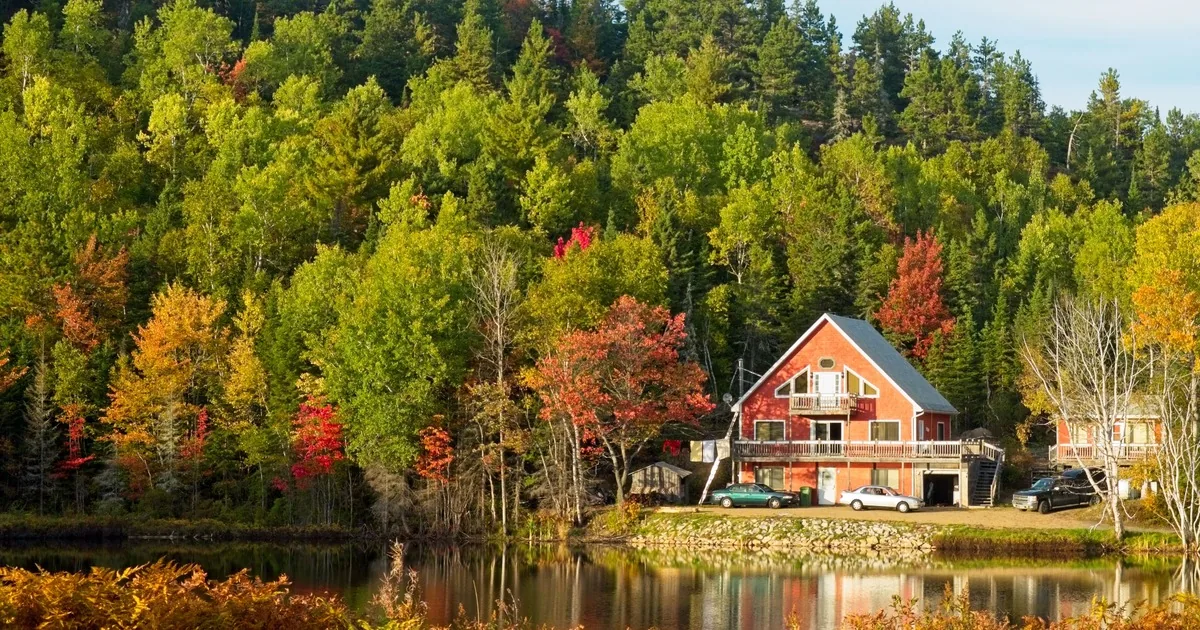
You found the camp. Now find out if it will finance.
Scrolling through Maine camps for sale is the fun part. The listing photos show the dock and the sunset. They do not show whether the road gets plowed, whether the water line is drained every October, or whether the septic was ever permitted. Those are the things that decide whether a camp gets a mortgage, and they are a lot cheaper to find out before you sign a purchase and sale agreement than after the appraisal.
I'm Travis Penny, a Maine and Florida mortgage broker with Vision Mortgage. I'm not tied to one bank. I compare multiple lenders for your loan and then stay with it myself, start to finish. Maine is home, and camp files are a big part of what I do here.
Camp, cabin, cottage or lake house: what the lender cares about
The word on the listing does not matter much. A log cabin in the woods, a cottage on the coast, a lakefront camp and a four season lake house all get judged on the same few questions.
Is it year round or seasonal? To finance a camp as a second home, it has to be suitable for living in year round. That usually means a permanent heat source, water that works in winter, and a real foundation. A three season camp on posts with a woodstove and a summer water line is a different conversation.
Can you reach it all year? A town road that gets plowed is the easy case. A private camp road can work too, and I want to see any road association papers or maintenance agreement early. A camp you can only reach by boat or a seasonal road is harder.
Where does the water come from, and where does it go? A drilled well and a permitted septic system make for a clean file. Camps that pull water straight from the lake, or that have an old system nobody can find paperwork for, need more work and sometimes a different loan.
Does the appraisal hold up? Lakefront camps can be hard to appraise because few sell each year and no two lots are alike. Frontage, the view and the water quality all move the value. I look at what has sold on the same lake or nearby lakes before you make an offer.
Shoreland zoning and older camps
Many Maine camps were built long before today's shoreland rules. A camp sitting closer to the water than current setbacks allow can still be financed as a legal nonconforming structure when the appraisal accounts for it. What I want to know is whether it could be rebuilt in the same spot if it burned, and whether any past additions or a new deck went through the town. Your local code enforcement officer is the person who answers that, and asking early saves surprises.
Older camps also come with older wiring, roofs and foundations. If the appraiser flags repairs, the loan may need them done before closing. I would rather talk through the inspection with you up front than watch a deal stall at the end.
Camps on leased land
Some Maine camps sit on a leased lot. You own the camp and rent the land underneath it, often from a large landowner or a family trust. These can sometimes be financed, but the lease terms matter: how long it runs, whether it can be renewed, and what happens to the camp if the lease ends. My page on leased land home loans walks through what I review.
Second home or primary home
How you plan to use the camp decides the loan.
Second home. You keep your main house and use the camp yourself part of the year. It has to be a single unit and it cannot be run as a rental. Conventional second home guidelines generally start at 10% down on a one unit home. That is a general guideline and not everyone will qualify. My vacation home loans page covers the occupancy rules in more detail.
Primary home. If you are moving to the lake full time, more programs open up, including FHA, VA and USDA when the camp and your file meet their rules. Those programs have their own property standards on heat, water and access, so the same camp questions still apply.
Rental. If the plan is to rent the camp out most weeks, that is an investment property and a different loan. Investors can start with my DSCR investor loans page.
Using a HELOC on your house to buy a camp
A lot of camp buyers already have equity in the house they live in. A HELOC on your Maine home, or a lump sum Maine home equity loan, can cover the camp purchase or a big down payment. That helps most with camps that would struggle to get a mortgage on their own, like a seasonal camp or one with boat only access, because the loan sits on your house and not on the camp.
This works when your primary home is in Maine or Florida. If you live in Florida, my Florida HELOC page covers the line there. I'll run the numbers both ways: a mortgage on the camp versus borrowing against your house.
Building or rebuilding a camp
Sometimes the camp is really a lot with an old structure on it. If you want to tear down and build a year round home, or you own land on a lake and want to build, a one time close construction loan wraps the build and the permanent mortgage into one closing. See my one time close construction loans in Maine page.
Maine lake regions I see camp files from
These are public geography facts that shape the loan file.
Sebago Lake. Maine's deepest lake and the drinking water supply for the Portland area. Towns around it, like Standish, Windham, Raymond, Naples and Casco, enforce shoreland rules closely. Sebago Lake real estate runs from year round homes to small seasonal camps, and Frye Island is a seasonal town reached by ferry, which matters for a second home loan.
Moosehead Lake. Maine's largest lake, with Greenville at the south end and Rockwood on the west shore. Many camps sit on private or logging roads, some are reached only by boat, and some are on leased lots. Access is the first thing I ask about here.
Rangeley Lakes. Rangeley Lake, Mooselookmeguntic and the lakes around them in Franklin County get long, snowy winters. Year round homes and seasonal camps sit side by side, so heat and winter road access decide a lot.
Belgrade Lakes. A chain of lakes in Kennebec County, including Great Pond, Long Pond and Messalonskee Lake, within reach of Augusta and Waterville. More of these camps have been converted to year round homes, and many sit on association maintained camp roads.
Downeast lakes. Graham Lake and Green Lake near Ellsworth in Hancock County, and West Grand Lake around Grand Lake Stream in Washington County. Fewer sales means fewer comparable sales for the appraiser, so I look at value early. If you're looking near the coast, my Mount Desert Island second home loans page covers the island.
What to send me before you make an offer
Send me the listing and a few answers, and I'll tell you plainly whether I see a path:
- The listing link or address
- Whether it will be a second home, your primary home or a rental
- The road: town road, private road with an association, or seasonal
- The heat source and whether the water works in winter
- Well, lake water or shared water, and what you know about the septic
- Where your current home is, if a HELOC might be part of the plan
If the listing is getting attention, I can turn this around fast and get you a preapproval letter so your offer is taken seriously. I started in 2004 and I'm still here. Call or text me at (207) 615-7770, email travis@travis.mortgage, or use my contact page. For a deeper look at the property side, read my blog post on financing a Maine camp or lake house.
Frequently asked questions
Can I get a mortgage on a camp for sale in Maine?
Yes, many Maine camps can be financed as a second home or a primary home. The camp needs to be suitable for year round living, with access the appraiser accepts and working water and septic. I check those before you make an offer. Not everyone will qualify.
Can I finance a seasonal camp that is not winterized?
It is harder. Second home loans generally need a camp that is suitable for year round use. If the camp is truly three season, using a HELOC or home equity loan on your primary home is often the cleaner way to buy it.
How much do I need to put down on a Maine lake house as a second home?
Conventional second home guidelines generally start at 10% down on a one unit home. That is a general guideline and not everyone will qualify. Your credit, reserves and the property itself all affect the final number.
Can I buy a camp on a private road in Maine?
Often, yes. I ask for any road association papers or maintenance agreement early, and Maine law also sets default upkeep duties for owners on a private road. Seasonal roads and boat only access are harder and need a closer look.
Can I finance a camp on leased land in Maine?
Sometimes. You own the camp and lease the lot, so the lease length, renewal terms and what happens at the end of the lease all matter. My leased land home loans page explains what I review.
Can I use a HELOC on my house to buy a camp?
Yes, if your primary home is in Maine or Florida and has enough equity. The line or loan sits on your house, not the camp, which can help with camps that would be hard to finance on their own. Not everyone will qualify.
Can I rent out my camp when I'm not using it?
A second home has to be for your own use and cannot be run as a rental. If renting is the main plan, it is an investment property and a different loan. I'll tell you which fits before you apply.
I live out of state. Can you finance a Maine camp for me?
Yes. Plenty of camp buyers live somewhere else. What matters is that the camp is in Maine and you'll use it yourself, so you can work with me by phone, text and email from wherever you live.
Keep exploring
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want a real human to walk you through this?
I'll lay out your options in plain English. No pressure, no scripts.