

Amy Hill
Travis Penny was very informative. He walked me through the whole process step by step. I highly recommend his services. I'm very grateful for his time and pati...
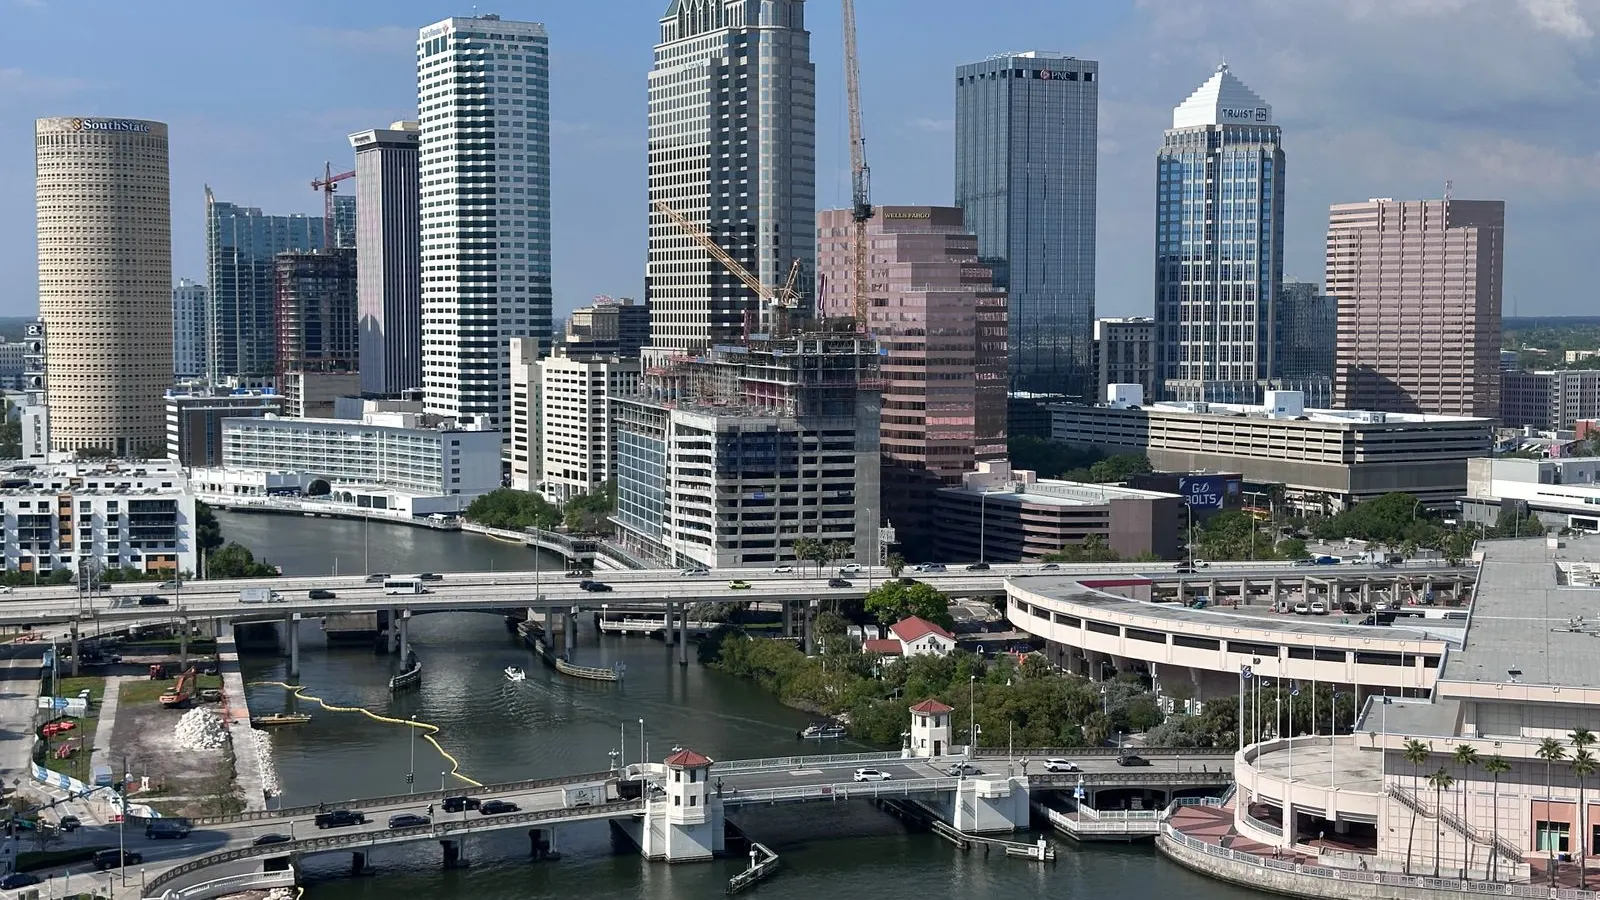
I arrange Tampa home loans for primary homes, second homes and eligible investments. I compare the documents needed for South Tampa houses, Channelside condos and New Tampa communities before recommending financing.
Written by Travis Penny, Senior Mortgage Broker, NMLS #1649161
Last reviewed November 14, 2026
I arrange Tampa home loans for primary homes, second homes and eligible investments. I compare the documents needed for South Tampa houses, Channelside condos and New Tampa communities before recommending financing.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a Senior Mortgage Broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
Hyde Park and Palma Ceia buyers may compare older detached homes with townhomes or condominium ownership. An older roof or remodeled room calls for inspection and permit review. A condo calls for the association budget, insurance and reserves. South Tampa's proximity to the bay also makes an address specific flood and insurance review important. Do not use the flood status of a neighboring block as evidence for your parcel.
For a buyer relocating near MacDill, clarify the timing and intended occupancy. An eligible service member can ask about VA financing, but a VA condo must meet the applicable project requirements. The property's condition still matters. Bring the exact listing and any association information into the financing discussion instead of assuming a neighborhood is automatically eligible.
Source: Hillsborough County property search.
Read more: Florida VA home loans.
A Seminole Heights bungalow can have renovations from different owners and different periods. Ask for permit records, inspect the roof and mechanical systems and confirm what will remain with the sale. If the home has a detached structure, find out its permitted use rather than assuming it can serve as a separate dwelling or rental.
Historic character does not establish financing eligibility. A property condition issue may affect an FHA or conventional review, while a permitted improvement and an unpermitted change can require different next steps. Ask the city about its applicable permit history and get professional inspections before making promises in an offer.
Source: Tampa construction services.
Read more: Florida FHA guide.
A Channelside condo purchase requires a project level look at insurance, reserves, assessments and occupancy restrictions. In Ybor City, a converted building or older house can raise questions about the property's legal use and renovations. Ask for the deed, permits and association documents when applicable. A walkable location does not settle the home's legal property type.
If you intend to rent a unit, check the building rules and local requirements before relying on rental income. A primary residence, second home and investment have different financing considerations. The right review starts with the specific building and how you will actually use it, not the neighborhood's popularity.
Source: City of Tampa planning resources.
Read more: Florida non warrantable condo guide.
In Westchase and New Tampa, check the property's jurisdiction and governing documents before assuming the same association obligations apply across a whole mailing area. A newer house may involve community rules or a district charge. Request the association packet and parcel information so those obligations are not discovered after an offer.
Ask for the actual insurance information even on a property farther from the waterfront. A newly completed house also needs a review of its builder contract and completed condition. Comparing an established home with a new build is easier when the site work, community obligations and title documents are available at the outset.
Source: Hillsborough County property appraiser.
Read more: Florida one time close construction guide.
A buyer eligible for VA financing near MacDill can review that path after clarifying occupancy and property condition. An owner occupant buying an eligible existing home can also compare FHA and conventional options. On a condo, the project documents may decide whether a conventional path works. I compare options based on the actual home, not an assumption that one program fits every Tampa address.
Before making an offer, get the parcel record, permit history when renovations matter, association information for shared ownership and address specific insurance guidance. If you are moving from Maine, identify when each home will be occupied. That makes the financing discussion about your real plan rather than a generic relocation label. I also help buyers considering Sun City Center, the 55+ community south of Tampa.
Read more: Florida conventional mortgages, Florida FHA mortgages, Maine to Florida relocation.
Nearby, I also cover Bradenton home loans and Sarasota home loans. My Florida home loans hub covers every program.
A condo may qualify if the buyer is eligible and the project meets VA requirements. Check the specific building before relying on that path.
Request inspection and permit records for renovations, and review the roof and other existing systems for the particular home.
No. Obtain the condo association's budget, insurance and assessment records for a shared building. For a house, inspect its condition and review relevant permits.
Travis Penny was very informative. He walked me through the whole process step by step. I highly recommend his services. I'm very grateful for his time and pati...
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
I'll lay out your options in plain English. No pressure, no scripts.
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.