
Marcus Lefebvre
Five star rating, no written review.
12.4 business day average to clear to close
Average of my loans from submission to clear to close. Not a guarantee; individual timelines vary. Clear to close means underwriting is done. Closing is scheduled after that.
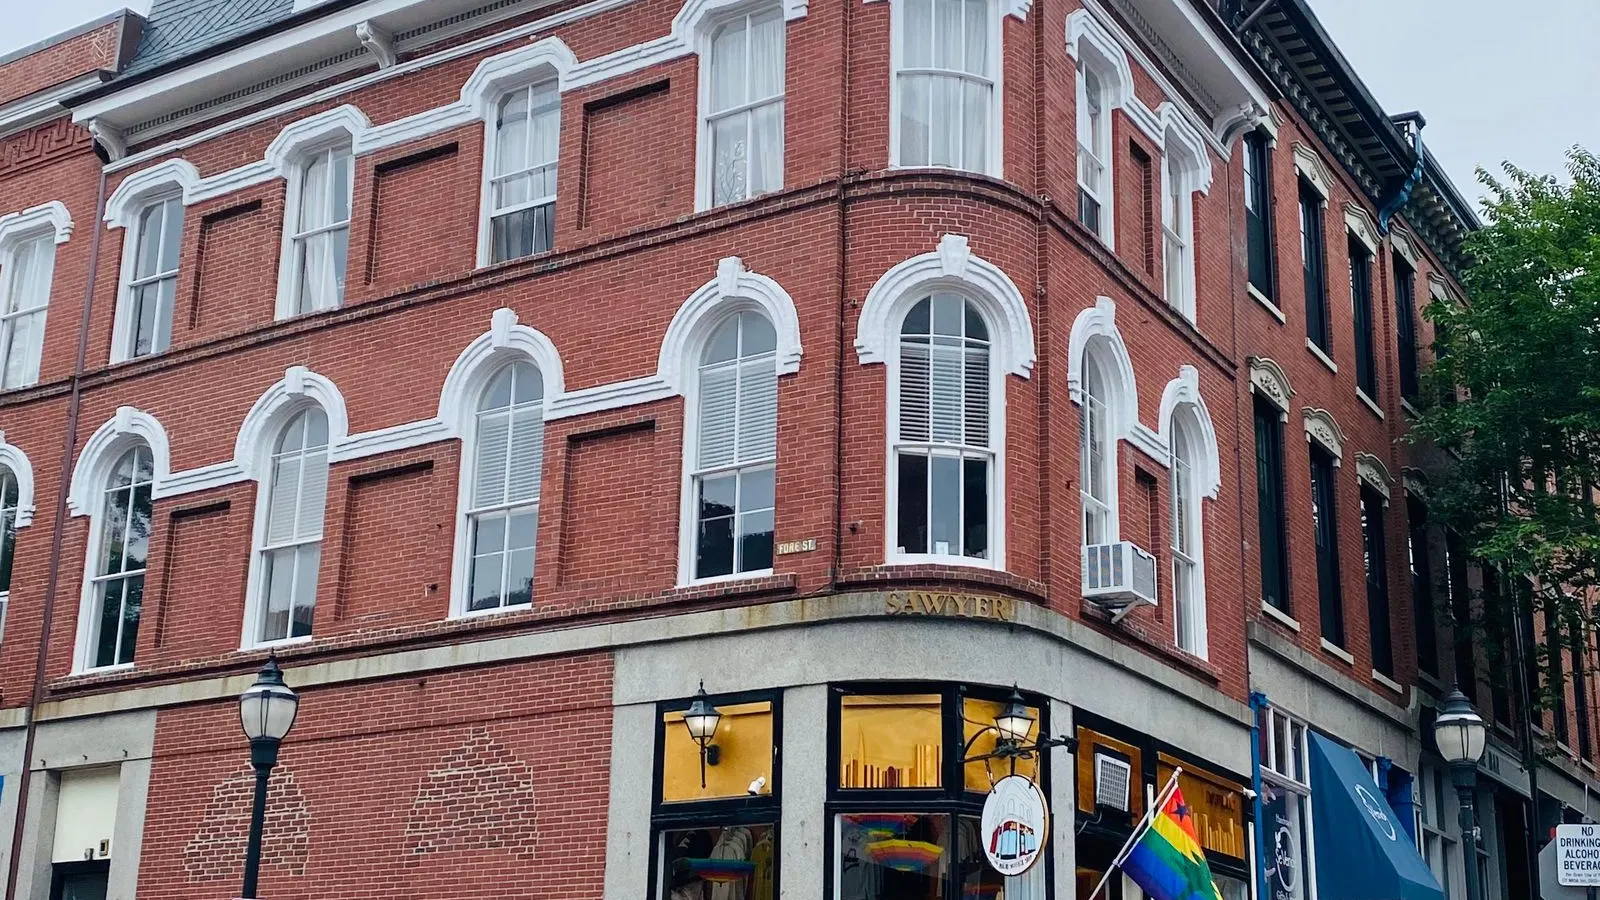
Portland, Maine
If you are comparing mortgage lenders in Portland, ME, I can compare several lenders' options with one application. I am a mortgage broker, not a bank, and I review your income, credit and the Portland property before recommending a program.
Reviewed by Travis Penny, NMLS 1649161
Last reviewed October 20, 2026
If you are comparing mortgage lenders in Portland, ME, I can compare several lenders' options with one application. I am a mortgage broker, not a bank, and I review your income, credit and the Portland property before recommending a program.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
Closing loans across Cumberland County and the rest of Maine. Real local underwriting know-how, no call centers.
FHA, VA, USDA, conventional, jumbo, and self employed bank statement loans. Matched to your file, not the easiest one.
You talk to me from pre approval through closing. No handoffs to a processor in another time zone.
I work on your side of the table. I don't lend money myself. I work with multiple lenders and bring their options to you, so the same file can go to several of them and I compare the offers side by side.
Here is what I handle for clients, from application to closing.
You'll receive a Loan Estimate within three business days of your application. You'll receive your Closing Disclosure at least three business days before closing. Those two documents are your checkpoints, and I go through both with you line by line.
A broker can't approve your loan. The lender that funds the loan makes the final credit decision after underwriting. A broker is usually paid a loan specific fee or commission, and every fee shows up on your Loan Estimate and Closing Disclosure before you sign. For more, see how a mortgage broker compares with a bank in Maine and what a mortgage broker costs in Maine.
One time close construction (conventional, FHA, VA). For a Portland build, check the lot's zoning, access, and utility connections before comparing conventional, FHA, or VA construction financing.
Bridge loans for buying before selling. A peninsula condo purchase may need association review while you arrange the sale of your current Portland home.
DSCR investor loans. For a Portland rental or multi unit, review actual leases, taxes, insurance, and any condo rental restrictions.
Physician and nurse loans. Portland healthcare workers can compare physician and nurse options while checking condo or older home property requirements.
Bank statement and 1099 loans. For a Portland buyer with business income, match bank deposits or 1099 records to the property and financing plan.
Read my guide to a second home loan in Maine.
Peninsula condos may require a review of the building and its association. An off peninsula single family home calls for a different property review. Portland also has older housing stock, so it is worth checking the roof, heating system, paint, and any well or septic details where applicable before you depend on a financing plan.
I also help buyers looking nearby in South Portland, Westbrook, Falmouth, and Cape Elizabeth. Call, text, or email me about the property you are considering.
Official sources: Portland Assessor's Office, FEMA Flood Map Service Center
The fastest first step is a five-minute scenario call. Bring your target purchase price, your down payment plan, and any credit concerns. I'll quote a realistic rate, payment, and cash-to-close range on the spot.
For 2026 HUD sets the FHA one unit floor at $541,287 and FHFA sets the conforming one unit baseline at $832,750 (HUD Mortgagee Letter 2025-23, December 11, 2025. FHFA release, November 25, 2025). Cumberland and York counties carry a higher FHA limit than the floor because of the Portland area's prices. I confirm the exact county figure on your file before you shop.
It depends on the file and the offers. A bank typically offers its own programs, while I compare options from multiple lenders. I review the same property, costs and terms so you can make a useful comparison rather than assume either choice is always better.
Compare written Loan Estimates for the same scenario, including costs, terms and mortgage insurance. Ask who will handle your file and whether the program fits the actual home or condo. I explain the differences and the remaining property or documentation questions.
Ask the city assessor for the current assessment and tax information for the actual parcel. A prior owner's bill may not reflect a reassessment or changes to the property. I use current information when reviewing your housing budget.
I check the flood determination for the exact address. A property in a designated special flood hazard area generally requires flood insurance with mortgage financing. Waterfront proximity alone does not settle the question.
Possibly, if the project is approved or the unit meets the applicable single unit approval rules. I review the building and association documents before you rely on FHA financing.
I check the actual address on the USDA eligibility map and review household income separately. I do not promise eligibility from the city name, and nearby addresses can have different results.
Portland uses Cumberland County limits. FHA limits vary by county and unit count, and conventional conforming limits are updated annually. I confirm the limit for your file before you depend on a program.
Check the NMLS number through NMLS Consumer Access before sharing personal documents. My individual NMLS is 1649161 and Vision Mortgage's company NMLS is 1286953.
Five star rating, no written review.
Travis was great to work with. We were able to close in less than three weeks.
Travis by far is the best Mortgage Broker I have ever worked with. I am happy to refer Travis to friends and family.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
I'll lay out your options in plain English. No pressure, no scripts.