
Manufactured home financing
How to get a loan for a mobile home in Maine or Florida
To get a mortgage on a mobile or manufactured home, the home usually needs to be built after June 15, 1976 to the HUD code, sit on a permanent foundation, and be titled with the land as real estate. If it is, I review FHA, VA, USDA and conventional options for a primary home in Maine or Florida, and conventional options for an eligible second home.
Travis Penny, mortgage broker, NMLS 1649161 | Vision Mortgage, LLC, NMLS 1286953
Reviewed by Travis Penny, NMLS 1649161
Last reviewed October 20, 2026
Mobile home vs manufactured home vs modular
People use mobile home for several kinds of factory built housing. For a mortgage, the building standard matters more than the name in the listing.
A manufactured home is built in a factory to the federal HUD code, which took effect June 15, 1976. A home built before that date is usually called a mobile home and does not fit the manufactured home mortgage options described here.
A modular home is built in sections to state and local building codes, like a house built on site. It is a different property category. My modular home financing guide covers that path.
I review primary and second home financing in Maine and Florida only. The home still has to qualify for its own program, and FHA, VA and USDA require primary home use.
All loans are subject to credit and underwriting approval. Not all applicants will qualify. Program terms and availability can change. This page is for general education and is not a loan offer or a commitment to make a loan. Travis Penny, NMLS ID #1649161, is a mortgage broker with Vision Mortgage, LLC, NMLS #1286953. Equal Housing Opportunity.
What makes a mobile home financeable
Before I discuss loan choices, I check whether the home can secure a real estate mortgage. Start with the property records, not just the seller's description.
- HUD label and data plate. These help identify the home's construction standard and original information. Tell me if either is missing so I can review what documentation is needed.
- Build date. The June 15, 1976 HUD code boundary matters. I need the actual year and available records.
- Permanent foundation. The foundation must meet the chosen program's requirements, with certification when required.
- Real property title. The home and land generally need to be treated as real estate rather than a home titled only as personal property.
- Owned or leased land. Owning the lot and leasing a park space are different financing situations.
In a park or on a leased lot? Start with my leased land home loans guide. That is where I explain leasehold reviews, including Florida 55+ communities. An ordinary lot rental agreement does not automatically give the home the recorded interest needed for a mortgage.
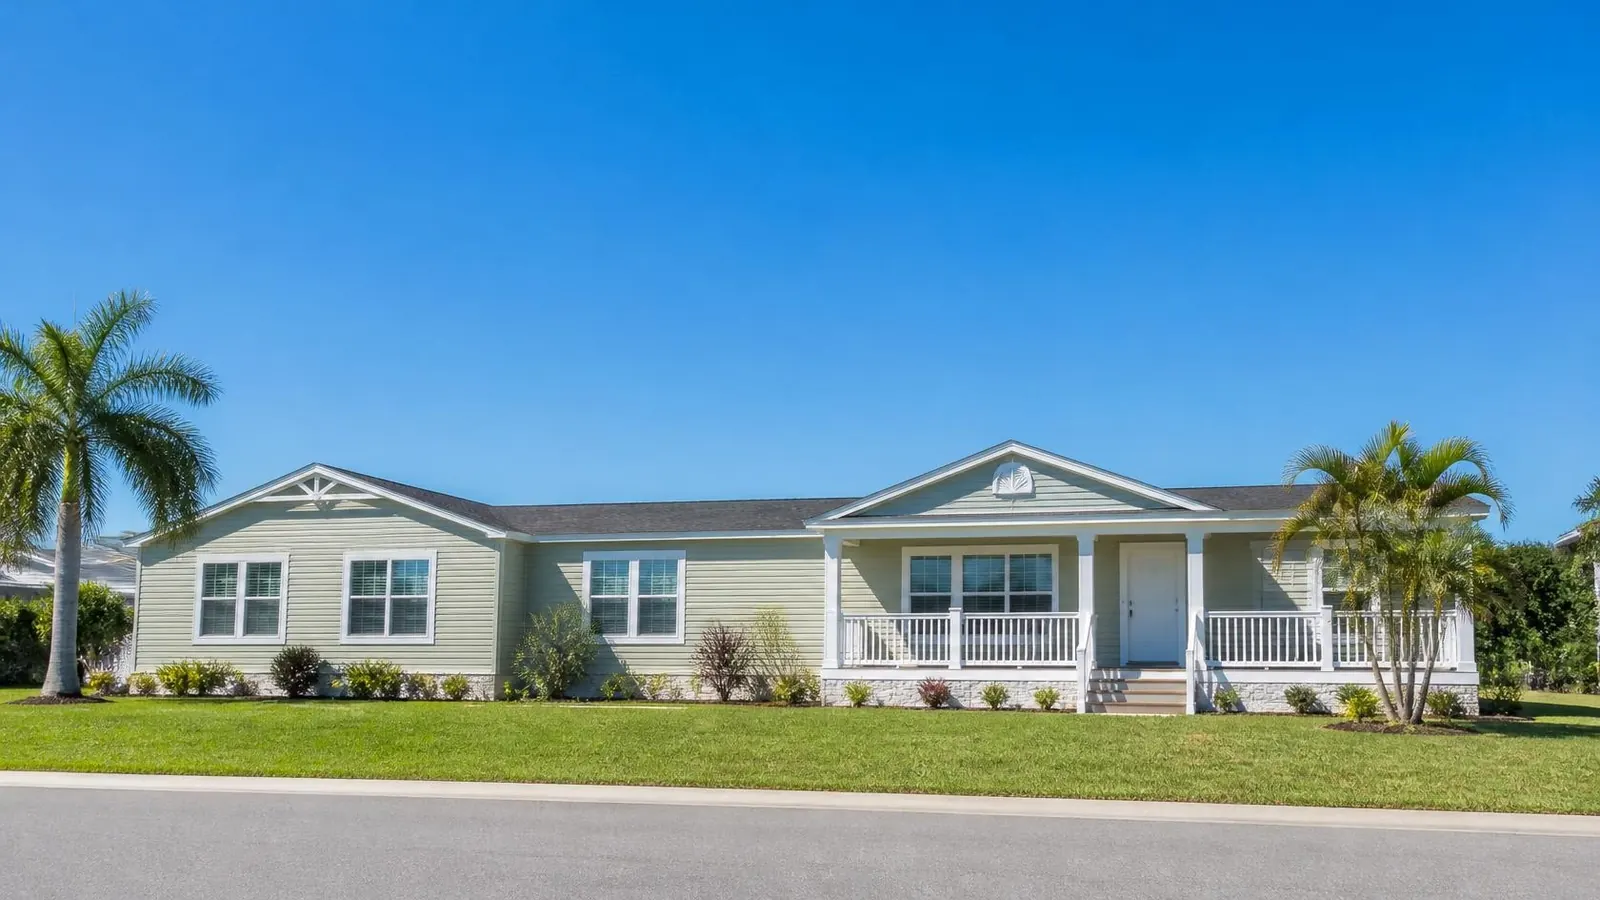
I need the home, lease and title to fit together. I will not treat every park home as eligible just because it is a double wide.
Double wide and single wide financing
Double wides on owned land are the most common manufactured homes to finance. They still need the right construction standard, foundation, title and condition. The section count alone does not establish eligibility.
Single wides can be harder. Availability depends on the program and the property, so send me the listing before assuming a mortgage will work. I also want to know whether the home is on its original site and whether it has additions.
For double wide mobile home financing in a community, the land arrangement matters as much as the home. I review that separately from a double wide sold with its own lot.
Credit that isn't perfect
FHA is often the most forgiving program for manufactured homes. I look at the full file: credit history, income, debts, available funds and the home itself. Not everyone will qualify.
If you are looking for manufactured home loans for bad credit, I would rather review your actual situation than give you a promise based on a phrase. A recent credit problem and an older one are not the same file. Neither tells me whether the property qualifies.
I will explain whether there is a workable option now or what needs attention first. A home that cannot meet the property rules does not become eligible just because the buyer's credit improves.
Loan options in Maine and Florida
For a primary home, I review the available programs against your eligibility and the property. These are not interchangeable, and not every manufactured home fits every program.
- FHA loans for a Maine primary home and Florida FHA options include credit, income and property review.
- Maine USDA loans require an eligible address and household income. For a Florida property, I check the same location and program questions at the actual address.
- Maine VA home loans and VA loans in Florida are for eligible buyers using the property as their primary home.
- Conventional financing can be considered for an eligible primary or second home, with its own manufactured housing requirements.
Buying your first home? My Maine first time buyer guide and Florida first time home buyer guide cover the broader purchase process. I review mobile home loans in Maine and mobile home loans in Florida with the specific property in front of me.
For a second home, I check that the program permits second home occupancy. FHA, VA and USDA are not second home programs.
When a mobile home can't get a mortgage
Some homes will not fit a real estate mortgage. A home built before the HUD code, a home without a qualifying permanent foundation, or a home titled only as personal property may be outside these programs.
Some park lots also cannot support a mortgage because the lease and title do not provide the required interest in the property. A sales listing that says financing available is not enough to settle that question.
I will tell you on the first call what I can see and what needs checking. Send the details before paying for inspections or depending on an approval. If a mortgage is not a workable path, I will say so.
What to send me
Send what is available and tell me what is missing. I can identify the next property question without asking you to guess.
- Listing link or property address
- Year built and whether it is single wide or double wide
- HUD label and data plate details, if available
- Foundation information or an existing certification
- Whether the land is owned or leased
- For a leased lot, the community name and lease details
- Whether you will live there as your primary home or use it as a second home
Call or text me about the home, or use my contact page. I will review the property basics first and tell you how to provide any personal documents securely.
Frequently asked questions
How do I get a loan for a mobile home?
Start with the address, year built, HUD label or data plate information, foundation and title. A manufactured home built to the HUD code after June 15, 1976, on a permanent foundation and titled with the land as real estate can fit a mortgage program. I review the property and your full file before recommending a loan.
Can I get a mortgage on a mobile home in a park or on leased land?
Sometimes, but many homes on ordinary rented park lots will not qualify for a mortgage. The home, foundation, lease, title and community all need to fit the program. Send me the listing and lease details first. My leased land home loan guide explains the separate review for Maine and Florida, including Florida 55+ communities.
Can I finance a double wide?
Yes, an eligible double wide on owned land can be financed when the HUD code, permanent foundation, real estate title and property requirements are met. Double wide mobile home financing still needs a review of your credit, income and the actual home. A double wide in a park needs a separate lease and title review.
Can I get a manufactured home loan with bad credit?
Possibly. FHA is often the most forgiving program for manufactured homes, but I review your full credit history, income, debts and the property. A search for manufactured home loans for bad credit is not an approval standard. Not everyone will qualify. I will tell you what fits and what would need to change.
What is the minimum down payment for a manufactured home?
FHA has a 3.5% minimum down payment for eligible buyers. VA and USDA can allow no down payment for eligible buyers and eligible primary homes. Conventional requirements depend on the property, occupancy and full file. Not everyone will qualify. A second home requires a program that allows second home use, not FHA, VA or USDA.
Does a mobile home need to be on a permanent foundation?
For the mortgage options I review here, a manufactured home needs a permanent foundation that meets the program's requirements. A foundation certification may be required. Removing the wheels or adding skirting is not proof that the foundation qualifies. I review the foundation and real estate title together.
Can I use the loan for a second home in Florida?
An eligible manufactured home in Florida may fit conventional second home financing. I check the property, title, foundation and your intended use. FHA, VA and USDA are primary home programs, so they are not the second home path. A home on a leased lot needs an additional leasehold review.
Keep exploring
Buying a manufactured home in Maine or Florida? Call or text me and I'll check the home and your options.
Not sure which loan fits?
Answer seven quick questions and I'll point you to the right program.
Want me to check the home before you make an offer?
I'll lay out your options in plain English. No pressure, no scripts.